For most people leaving StatesCard, Halocard is the best alternative: a US-issued Visa credit card that clears US checkouts, with 0% fees on dollar purchases and no US residency required. US Unlocked is the closest prepaid substitute, Privacy.com wins for US residents who want merchant locked cards, and RedotPay suits crypto spenders. The right pick comes down to where you live and how you want to load funds.
If you are hunting for the best StatesCard alternatives, you probably hit one of its two walls: the fees or the reliability. StatesCard is a virtual prepaid Visa debit card, issued by a US bank, that gives people outside the United States a US card number and a Delaware billing address to pay for streaming, app stores, gaming, and US shopping that a foreign card cannot complete. Useful in theory, but newer virtual card providers now do the same job more cheaply and more reliably.
The fees are the first problem: a $16.99 issuing fee, a $3.95/month fee, and load fees of 7.5% on credit cards and 8.5% on PayPal, though StatesCard notes those load fees are set by the payment networks and issuing bank rather than by StatesCard itself. The second is reliability, with a Trustpilot score of 2.1/5 from 57 reviews and recurring reports of cards being revoked without replacement and balances left stranded.
To be fair, StatesCard is a legitimate, long-running service rather than a scam, and independent domain scanners flag no fraud; the case for switching is about cost, card flexibility, and support, not safety. This guide compares ten virtual card and payment services that solve the same problem with fewer of those headaches, so you can match a payment method to your situation rather than guessing.
Key Takeaways
-
Halocard is the best all-round alternative. US-issued virtual Visa cards in 120+ countries, 0% on USD purchases, no SSN for non-US residents, and a custom billing address on every card.
-
The right choice depends on your goal. US Unlocked is the closest prepaid substitute, Privacy.com leads for US residents wanting merchant locked cards, RedotPay and SiraPay suit crypto funding, and Wise or Revolut fit multi currency needs.
-
Beat the load fees, not just the monthly fee. StatesCard's 7.5% to 8.5% load charges are the number to undercut; several alternatives let you load funds by crypto, bank transfer, or card for far less.
-
Virtual cards cut fraud risk by design. Masked card numbers, disposable cards that close after one transaction, and merchant-locked cards all limit exposure as online fraud keeps climbing.
-
StatesCard is legitimate but outclassed. It still handles basic US streaming, yet its high fees, single-card model, and low review score make the stronger options below easy to prefer.
Quick Comparison Table
| Provider | Card / Account Type | Availability | Virtual Card Capacity | Key Pricing and Fees | Best For |
|---|---|---|---|---|---|
| Halocard | US-issued Visa virtual credit card | 120+ countries; no US residency; no SSN for non-US residents | 3, 12, or 60 personal cards by plan | $12–$75/mo personal; 0% USD, 1.5% + $0.30 non-USD; Card, Apple Pay, Google Pay, Bank Transfer, Stablecoins & Crypto | International users needing a reliable US virtual card |
| US Unlocked | US-issued virtual prepaid cards | International users in supported countries | Everyday, Store Locked, and one-time cards | $4.95/month or $39.95/year; loads 2%–5% plus fixed charges | Shopping US websites from abroad |
| Privacy.com | US virtual payment cards | US citizens/residents, 18+, with a US checking account | 12–60 new cards/month by plan | $0–$25/mo; 3% FX on lower tiers | US residents wanting merchant locked and disposable cards |
| RedotPay | Stablecoin-funded virtual/physical card | Reported 100+ countries | Account and card limits vary | $10 virtual card; $100 physical; Pro $12.90/mo | Crypto and stablecoin spenders |
| SiraPay | Privacy-focused virtual card | Claims 150+ country coverage | Up to 5 cards | Free plan; $0.99/mo or $4.99/yr card options | Low-cost, low-friction private cards |
| Wise | Multi-currency account + debit card | Broad international | Multiple virtual cards | No monthly fee; one-time card ~$9 US; mid-market FX | Cheap cross-border transfers plus card spend |
| Revolut | Multi-currency account + virtual/prepaid debit | UK, EEA, US and more (varies) | Up to 20 active; 5 new per 30 days | $0–$16.99/mo; fair-use FX after allowance | Multi-currency spending and disposable cards |
| Payoneer | Business payment account + Mastercard | Broad international; business users | Hundreds to thousands at scale | $29.95 annual card fee; up to 3.5% with conversion | Cross-border business earnings |
| Airwallex | Business account + Visa corporate cards | 20+ currencies; businesses in 69 countries | Unlimited corporate cards on US Explore | Explore $0; card user fees on higher tiers | Multi-currency business spending |
| N26 | European bank account + Mastercard debit | Supported European markets | Up to 6 active virtual cards | Free to €16.90/mo; extra card €2.59 on Standard | European digital banking |
Best StatesCard Alternatives for Virtual Cards and US Merchant Access
Below are the ten best alternatives to StatesCard, starting with the option that fixes the most common StatesCard complaints, then working through specialists for prepaid spending, US residents, crypto funding, and multi currency business needs.
1. Halocard
Halocard is a virtual card provider whose core product is a US-issued Visa virtual credit card, issued instantly, and available to people that most US card programs turn away. Where StatesCard hands you a single prepaid Visa and charges heavily to load it, Halocard verifies your identity and then lets you create virtual cards across a range of plans, each with its own spending limits, security code, and billing address. For an international shopper whose foreign card keeps failing US checkouts, it is the most direct upgrade on this list.
How Halocard Works
You register in a browser, no app required, and complete a quick identity verification step. Non-US residents can sign up from 120+ countries without an SSN, verifying with a passport or national ID in under three minutes, while US residents provide an SSN or ITIN. Phone numbers from any country are supported.
Once verified, you add money and generate virtual cards from the online account center, assigning each one a name, a spending limit, and a custom billing address. Cards are issued under Visa through Halocard's financial partners and work for online purchases, recurring payments, and in-person spending through Apple Pay and Google Pay at more than 175 million merchants, though no provider can guarantee acceptance at every individual store.
Halocard Costs & Fees
-
Essential: 3 virtual cards for $12/month, or $144/year
-
Pro: 12 cards for $15/month, or $180/year
-
Elite: 60 cards for $75/month, or $900/year
-
Business plans from $29/month (Core, 30 cards) up to $299/month (Enterprise, 500 cards)
-
USD online purchases: 0% purchase and FX fee
-
Non-USD purchases: 1.5% + $0.30 foreign transaction fee
-
Funding: debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto
-
Annual billing is the monthly price x 12, and Essential is free with 3 referrals
The contrast with StatesCard's 7.5% to 8.5% load fees and $3.95/month fee is stark. Fund Halocard with stablecoins and adding money costs nothing, and dollar purchases carry no transaction fees at all.
Halocard Spending Limits and Funding
Halocard works on a fund-first basis rather than a credit line, so your only spending ceiling is the balance you have added, and there is no credit check. You load funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto, with bank transfers in USD, CAD, EUR or GBP, then spend what you have. Per-card controls cover per-transaction, daily, and monthly spending limits, plus instant freeze and cancel, so you can shut down a card the moment a free trial threatens to convert. Loading funds via crypto also adds an extra layer of anonymity, since the deposit does not route through your main bank account.
Halocard Key Advantages
-
US-issued virtual Visa cards recognized as domestic at US checkouts
-
No US residency and no SSN required for non-US residents, and no credit check
-
Custom billing address on every card, which is what clears many US address-verification checks
-
Multiple funding methods, including stablecoins, crypto, cards, and bank transfer
-
0% fee on USD online purchases
-
Apple Pay and Google Pay support on every plan
-
Strong separation between your purchases and your primary account details, safeguarding your financial data
Halocard Specific Drawbacks
-
No cash back or rewards program
-
No native accounting integrations, bill pay, or receipt matching
-
An FX fee of 1.5% + $0.30 applies to non-USD spending
-
Multi-currency account features are limited, so it is not a full replacement for a bank account, though it includes a US bank account with its own account and routing numbers and a physical card is available: Physical card, free with any annual plan or $100 on a monthly plan
-
No permanent free plan unless you meet referral requirements
Who Halocard Is Best For
Halocard suits freelancers, digital nomads, international shoppers, SaaS and AI-tool buyers, media buyers running Facebook and Google Ads, and privacy-conscious users who need a dependable US virtual card that a foreign debit card cannot replace. It is covered in more depth in this guide to virtual cards with a US billing address.
Why Someone Would Choose Halocard Over StatesCard
The reasons stack up quickly. StatesCard charges up to 8.5% to load a card; Halocard charges 0% on USD spend. StatesCard carries a 2.1/5 Trustpilot score with recurring reports of stuck balances; Halocard holds a small but positive Trustpilot rating, 4.2/5 (11 reviews).
Halocard also gives you several cards with individual controls rather than one prepaid card, and a custom billing address on each. For anyone whose core need is a US card that consistently works, Halocard is the more reliable payment method, and our full Halocard vs StatesCard comparison breaks the two down side by side.
2. US Unlocked
US Unlocked is the closest direct competitor to StatesCard, offering US-issued virtual prepaid cards with a US billing address specifically for people shopping American websites from abroad. If StatesCard's concept appealed to you but its reliability did not, US Unlocked covers the same ground with a slightly broader card lineup.
How US Unlocked Works
You verify your identity, load a USD wallet, and create virtual cards from the dashboard. The service offers Everyday Spend Cards for general use, Store Locked Cards tied to a single approved merchant for recurring purchases, and One-Time Use Cards for disposable, single-transaction spending. Each card comes with its own card number, expiration date, and security code, and a US billing address to satisfy checkout checks.
US Unlocked Costs & Fees
-
Monthly plan: $4.95/month, or $39.95/year annually
-
One Everyday Spend Card included; additional cards $1/month each
-
One-Time Use Card: $2
-
Crypto or stablecoin load: 2%
-
Card, Apple Pay, or Google Pay load: 5% + $1
-
Non-USD foreign-currency transaction fee: 3%
-
Unload fee: $10; returned payment $30; maximum account balance stated at $3,000
Note that US Unlocked's own pages have shown conflicting figures for European bank-transfer loads, so confirm the displayed fee before adding money.
US Unlocked Spending Limits and Funding
This is a prepaid USD model, so you can only spend what you load, which naturally caps overspending. Store Locked Cards add spending restrictions for recurring purchases, and one-time cards close after a single transaction, preventing further charges. Funding runs through crypto, cards, and mobile wallets, with the fees above.
US Unlocked Key Advantages
-
US-issued virtual prepaid card with a US billing address
-
Purpose-built for international users paying US merchants
-
Merchant-locked and one-time card options for tighter control
-
Crypto funding available
-
3D Secure support and no credit check
US Unlocked Specific Drawbacks
-
Funding fees reach 5% plus fixed charges on card loads
-
A subscription is required even for light use
-
The $3,000 balance cap limits larger purchases
-
A 3% fee applies to non-USD merchant transactions
-
Customer sentiment is weak: a Trustpilot score of 1.9/5 from 114 reviews, with more than half at one star
Who US Unlocked Is Best For
US Unlocked fits non-US customers who mainly need to pay US ecommerce sites and digital services and want merchant-locked or one-time cards as well as everyday spend cards.
Why Someone Would Choose US Unlocked Over StatesCard
US Unlocked offers a lower entry price than StatesCard's $16.99 issuing fee, a wider set of card types including store-locked and disposable cards, and a 2% crypto load option that undercuts StatesCard's card and PayPal loads. Its review record is similar, so the case for switching rests on card flexibility and cheaper funding rather than a dramatically better reputation. For the strongest all-round reliability, compare both against Halocard, as laid out in Halocard vs US Unlocked.
3. Privacy.com
Privacy.com is a mature US virtual card platform designed around isolating each online purchase from your underlying checking account. It is the reference point for merchant locked cards, but it comes with one hard limit that rules out most StatesCard users: it is US-only.
How Privacy.com Works
Privacy is available to US citizens or legal residents aged 18 and over who hold a checking account at a US bank or credit union. International bank accounts and non-US users are not supported. Once linked, you create virtual cards that can be merchant-locked, single-use, or capped with transaction, monthly, annual, or total spending limits. A browser extension autofills card details at checkout, which makes generating a fresh card for each site nearly frictionless.
Privacy.com Costs & Fees
-
Personal: $0/month, up to 12 new cards per month
-
Plus: $5/month or $60/year, up to 24 cards
-
Pro: $10/month or $120/year, up to 36 cards
-
Premium: $25/month or $300/year, up to 60 cards
-
Personal and Plus foreign transaction fee: 3%, minimum $0.50
-
Pro and Premium: 0% FX, plus 1% cashback up to $4,500 a month
Privacy.com Spending Limits and Funding
Purchases draw from your linked US checking account, so this is not a prepaid or loaded balance. Individual cards can be capped or closed without touching your main bank account, and merchant-locked cards can only be used at the retailer you assign, which reduces fraud risk if a card number leaks. Single-use cards close automatically after one transaction.
Privacy.com Key Advantages
-
Excellent free tier for US residents
-
Merchant-locked cards that lock spending to one retailer
-
Single-use and disposable cards for one time purchases
-
Granular spending limits and a browser extension for fast checkout
-
Mature security and privacy controls, with a strong review record
Privacy.com Specific Drawbacks
-
US-only, requiring a US checking account, which excludes most StatesCard users
-
KYC and identity verification required
-
3% international transaction fee on the free and Plus tiers
-
No multi-currency or international transfer features
Who Privacy.com Is Best For
Privacy.com is ideal for US residents managing subscriptions, free trials, and online purchases who want merchant-specific card exposure rather than a single shared card number.
Why Someone Would Choose Privacy.com Over StatesCard
For a US resident, Privacy.com is simply a better product: a free tier, merchant-locked and single-use cards, and a Trustpilot score of 4.5/5 from 3,358 reviews, with roughly 89% at five stars. The catch is eligibility. If you are outside the US, Privacy.com is not an option and Halocard or US Unlocked will serve you instead. Privacy.com's merchant-locked model is a genuinely strong approach to subscription control, and it pioneered the category. We put it head to head with Halocard in our best Privacy.com alternatives roundup and in focused comparisons like Privacy.com vs IronVest vs Halocard and Privacy.com vs MySudo vs Halocard.
4. RedotPay
RedotPay is a crypto and stablecoin payment platform rather than a conventional card issuer, aimed at people whose money already lives in digital assets. The company reports more than 8 million users across 100-plus countries and says its cards are accepted at over 130 million merchants.
How RedotPay Works
You complete identity verification, fund a RedotPay balance with crypto or stablecoins, and issue a virtual or physical card. Virtual cards can be linked to Apple Pay, Google Pay, or PayPal, so once the card exists you spend through familiar digital wallets. This is one of the clearer examples of loading funds via crypto to enable international transactions while adding a layer of anonymity between your assets and the merchant.
RedotPay Costs & Fees
-
Virtual card issuance: $10 one-time
-
Physical card issuance: $100
-
RedotPay Pro: $12.90/month or $129/year
-
Pro gives 3% cashback on qualifying Apple Pay and Google Pay spending, capped at $18/month
-
Certain merchants, including Facebook Ads, incur a 1.5% transaction fee with a $0.50 minimum, after three monthly waivers per card (our roundup of the best virtual cards for Facebook Ads compares this against alternatives)
RedotPay Spending Limits and Funding
RedotPay is funded primarily through crypto and stablecoin balances, with swaps, transfers, and P2P features in the wider platform. Card limits vary by account tier and verification level.
RedotPay Key Advantages
-
Stablecoin and crypto funding for international spending
-
Virtual and physical card options
-
Apple Pay and Google Pay support
-
A large claimed global footprint and merchant network
-
A full crypto-to-payment ecosystem in one app
RedotPay Specific Drawbacks
-
Requires identity verification and is not a conventional bank account
-
Crypto-linked products add complexity and market risk
-
Some merchants carry extra transaction fees
-
Trustpilot score around 3.1 from roughly 750 to 800 reviews, with a high-risk-investment notice on the profile
Who RedotPay Is Best For
RedotPay is best for users whose financial life already starts with crypto and who want to turn stablecoins into everyday card spending.
Why Someone Would Choose RedotPay Over StatesCard
If you hold USDT or USDC and want to spend it directly, RedotPay converts crypto to card spending more smoothly than StatesCard, which is not crypto-native. RedotPay's broad acceptance is a genuine draw, and its paid Pro plan adds cashback that its free account doesn't pay. That said, its review profile is mixed, so treat it as a spending tool rather than a place to store a large balance. For a fuller comparison of a crypto-friendly card that also issues US credentials, see Redotpay vs Halocard, and for other crypto-funded prepaid options, our Ezzocard vs Halocard and Buvei vs Halocard comparisons cover the same ground.
5. SiraPay
SiraPay is a newer privacy-focused virtual card service marketed at freelancers, crypto users, and digital nomads who want minimal onboarding friction. It is the lightest-touch option here, with the trade-offs that come with a short track record.
How SiraPay Works
SiraPay says its onboarding does not require facial verification or a government ID upload, collecting only basic information for regulatory purposes. Because that differs sharply from most regulated providers, treat it as the company's current claim rather than a guarantee that further checks will never apply. You can create up to five virtual cards, and SiraPay's FAQ cites coverage across 150-plus countries and acceptance at more than 150 million merchants.
SiraPay Costs & Fees
-
Free-forever plan advertised
-
Monthly card option: $0.99/month
-
Yearly card option: $4.99/year
-
Up to five virtual cards
Its fees page lists a 1.5% fee on payments in a currency other than US dollars, but answers "Check the app" for card prices and top-up fees.
SiraPay Spending Limits and Funding
SiraPay's marketing mentions both crypto and fiat top-ups, but its detailed FAQ currently names Binance Pay (USDT) as the accepted deposit method, with more options promised later. Check the current funding options before you sign up.
SiraPay Key Advantages
-
Very low published card pricing
-
Up to five virtual cards
-
Privacy-first positioning with minimal onboarding
-
International-user focus and crypto-native funding
SiraPay Specific Drawbacks
-
Newer service with a limited operating history
-
Less transparent fee structure than established providers
-
Deposit options currently narrower than the marketing suggests
-
Country-coverage and onboarding claims should be verified for your location
Who SiraPay Is Best For
SiraPay suits users who prioritize low cost, crypto funding, and fast, low-friction onboarding, and who are comfortable with a younger service.
Why Someone Would Choose SiraPay Over StatesCard
SiraPay's $0.99 monthly card and free tier undercut StatesCard's $3.95/month fee and $16.99 issuing charge dramatically, and its onboarding is lighter. The trade-off is maturity and transparency: StatesCard has years of operating history, while SiraPay is still proving itself. For cost-sensitive users who want a private card and can accept some uncertainty, it is worth a look, ideally tested with a small balance first.
6. Wise
Wise, formerly TransferWise, is a multi-currency account with virtual and physical debit cards, best known for transparent, low-cost international transfers at the mid-market exchange rate. It is less a StatesCard replacement and more a broader financial tool, but for many international users it removes the need for a specialist US card entirely.
How Wise Works
You open an account, hold balances in more than 40+ currencies with local bank details in several, and issue virtual and physical debit cards. Cards spend in over 160 countries with automatic conversion at the mid-market rate, and you can hold multiple virtual cards, freeze them instantly, and assign each to a purpose. Transfers show a visible percentage fee rather than a hidden exchange-rate markup.
Wise Costs & Fees
-
No monthly subscription fee
-
One-time account opening fee, around €50 in the EEA, varying by region
-
Physical card issuance from roughly $9 in the US; virtual cards generally free
-
Transfer fees typically 0.33% to 1.0% of the amount
-
ATM withdrawals free up to a monthly threshold, then a small fee plus percentage
Wise Spending Limits and Funding
Wise cards operate on a balance model, so spending is limited to your available funds across currencies. You can create multiple virtual cards, freeze them, and auto-convert at spend time if the needed currency balance is empty.
Wise Key Advantages
-
No monthly fee and genuinely transparent pricing
-
Mid-market exchange rates with no hidden markup
-
Balances in 40-plus currencies and card spend in 160-plus countries
-
Multiple virtual cards, free to create
-
Broad international availability with no US-entity requirement
-
A Trustpilot score of 4.3/5 from 300,000+ reviews
Wise Specific Drawbacks
-
Not a US-issued card, so it is not optimized for US billing-address checks the way a dedicated US card is
-
No credit product, rewards, or cashback
-
Some ATM and conversion fees still apply
-
Not a spend management or subscription-control tool
Who Wise Is Best For
Wise is best for freelancers, travelers, and small international businesses whose priority is cheap cross-border payments and simple multi currency card spending rather than a card that specifically mimics a US billing profile.
Why Someone Would Choose Wise Over StatesCard
Wise wins on cost transparency and multi currency flexibility, with no monthly fee and no punishing load charges. It is a downgrade if your specific problem is a US billing address that foreign cards fail, since Wise issues a card from your home region rather than a US one. Where StatesCard is a narrow US-access tool and Wise is a broad money platform, Halocard sits between the two. That trade-off is explored in Revolut vs Wise vs Halocard.
7. Revolut
Revolut is one of the most complete Wise-style alternatives, combining international transfers, currency exchange, budgeting tools, and both regular and disposable virtual cards inside one app. For StatesCard users, its appeal is disposable cards and multi currency spending rather than US-specific access.
How Revolut Works
You create regular virtual cards instantly in the app, up to 20 active at once, with a limit of five new virtual cards in any rolling 30-day period. Revolut also offers a single-use disposable card whose details regenerate after each completed purchase or after 24 hours, though disposable cards cannot be used for subscriptions, recurring payments, deposits, ATMs, or mobile wallets. Regular virtual cards work with Apple Pay and Google Pay.
Revolut Costs & Fees
-
Standard: $0/month
-
Premium: $9.99/month or $94.99/year
-
Metal: $16.99/month or $149.99/year
-
Bank-transfer funding: no Revolut load fee; card funding up to 1% to 3%
-
Currency exchange: the first $1,000 per monthly cycle without a fair-use fee during market hours, then 0.5%, with 1% outside market hours
Revolut Spending Limits and Funding
Revolut checks the transaction currency, then your base balance, then another funded balance, helping you manage multiple currencies without converting before each purchase. Spending is limited to your available funds.
Revolut Key Advantages
-
Free plan with up to 20 active virtual cards
-
Disposable single-use card for one time purchases
-
Multi currency functionality and international transfers
-
Apple Pay and Google Pay
-
Budgeting tools, savings, and broader digital-banking services
Revolut Specific Drawbacks
-
Features and pricing vary considerably by country
-
Standard users hit fair-use and off-market-hours FX fees
-
Not designed to give non-US residents US-issued card credentials
-
Disposable cards cannot handle subscriptions
Who Revolut Is Best For
Revolut fits travelers, expats, and internationally active users who want disposable cards, budgeting, and multi currency spending in one app.
Why Someone Would Choose Revolut Over StatesCard
Revolut offers a free tier, disposable virtual cards, and genuine multi currency features that StatesCard cannot match, along with a Trustpilot score of 4.7/5 from 470,000+ reviews, though that figure is dominated by the consumer app broadly. Like Wise, it does not specifically solve the US-billing-address problem, so international shoppers who keep failing US checkouts may still need a US-issued card alongside it.
8. Payoneer
Payoneer is a business-focused cross-border payments platform built for freelancers, agencies, sellers, and companies receiving international payments. It is less about private online shopping and more about receiving revenue and spending it through cards.
How Payoneer Works
Eligible customers create virtual cards quickly and can issue hundreds, or thousands at scale, for advertising, suppliers, subscriptions, and other company spending. Cards spend directly from balances in USD, EUR, GBP, CAD, or JPY, so the workflow is receive, hold, then spend.
Payoneer Costs & Fees
-
Annual card fee: $29.95
-
Additional virtual cards: free
-
Purchases without conversion: up to 1.8%, with some same-currency purchases free
-
Transactions involving conversion: up to 3.5%
-
A separate $29.95 annual account fee may apply if the account receives less than $6,000 in a 12-month period
Payoneer Spending Limits and Funding
Corporate cards can support very high daily spending, subject to approval, and eligibility generally requires at least $100 received into the account in the previous six months. Payoneer does not currently issue cards to customers with addresses in Russia or India.
Payoneer Key Advantages
-
Business accounts for cross-border earnings
-
Hundreds of virtual cards, with free additional cards
-
Very high approved spending limits and no credit check
-
QuickBooks, Xero, and NetSuite integrations
Payoneer Specific Drawbacks
-
Business use only, not aimed at private shoppers
-
Annual card fee and a possible annual account fee
-
FX fees up to 3.5% with conversion
-
Trustpilot currently shows a guidelines-breach notice on the profile after fake reviews were removed
Who Payoneer Is Best For
Payoneer suits freelancers and businesses already paid by international clients or marketplaces who want to spend those balances through cards.
Why Someone Would Choose Payoneer Over StatesCard
Payoneer makes sense when your money arrives as international business revenue and you want to spend it without first moving it to a bank. For simple personal US streaming or shopping, it is heavier than you need, and StatesCard or, better, Halocard is a closer fit.
9. Airwallex
Airwallex is a global financial platform for businesses, offering multi currency accounts, low-markup FX, corporate cards, and expense management. Like Payoneer, it is a business tool rather than a personal US-access card, but it is one of the strongest options for cross-border companies.
How Airwallex Works
Businesses open Global Accounts with local details in 20-plus currencies, then issue unlimited virtual or physical Visa corporate cards. Cards can be linked to specific currency wallets to avoid unnecessary conversion, and spending controls and approval workflows apply per card.
Airwallex Costs & Fees
-
Explore: free in the US, with conditions in other regions
-
Grow: around $12 per active spend user per month plus a platform fee
-
FX markup: 0.5% on major currencies, 1.0% on others
-
No international transaction fees on cards, with 2% cashback on eligible spend under promotional terms
Airwallex Spending Limits and Funding
Card limits are configured per card and per wallet, funded from multi currency balances rather than a credit line. Unlimited virtual and physical cards are available subject to plan, with instant issuance, freeze, and Apple Pay and Google Pay support.
Airwallex Key Advantages
-
Low FX markup versus traditional banks
-
Multi currency accounts in 20-plus currencies with local details
-
Genuinely global, with no US-entity requirement
-
Corporate cards, expense management, and payment acceptance in one place
Airwallex Specific Drawbacks
-
Built for businesses, not personal shoppers
-
Free access outside the US is conditional on balances or deposits
-
Reviewers report account reviews and held funds in some cases
-
Trustpilot score around 3.0 from roughly 2,530 reviews
Who Airwallex Is Best For
Airwallex fits businesses that move money across borders and need multi currency accounts and corporate cards together, including companies with no US entity.
Why Someone Would Choose Airwallex Over StatesCard
For a cross-border business, Airwallex replaces a stack of tools and offers far better FX economics than a prepaid card. It is overkill for a single person trying to pay for a US streaming service, where a dedicated US virtual card from Halocard or StatesCard is the right size of tool.
10. N26
N26 is a licensed European digital bank rather than a specialist virtual card service. It earns a place here for European users who want a real bank account with virtual and physical debit cards, though it does nothing to provide a US billing address.
How N26 Works
N26 Standard includes one free virtual Mastercard once you hold a one-time €10 activation balance. Standard customers can add extra virtual cards for €2.59 each, up to six active cards, while paid plans include extra virtual cards at no charge. Cards spend directly from your N26 account and work with Apple Pay, Google Pay, Samsung Pay, and Garmin Pay.
N26 Costs & Fees
-
Standard: free
-
Smart: €4.90/month
-
Go: €9.90/month
-
Metal: €16.90/month
-
Standard and Smart apply a 1.7% fee on non-euro ATM withdrawals; Go and Metal waive it
N26 Spending Limits and Funding
Cards spend from your N26 balance, and paid plans include up to 10 Spaces sub-accounts for organizing money and budgeting toward goals.
N26 Key Advantages
-
A full European bank account with deposit protection
-
A free virtual card on Standard, up to six virtual cards
-
Physical debit cards and broad mobile-wallet support
-
Budgeting automations and sub-accounts
N26 Specific Drawbacks
-
Limited to supported European markets
-
Not a solution for US-issued virtual cards or a US billing address
-
Premium features require monthly fees
-
Trustpilot rating of 4.2/5 from 43,100 reviews, but with a notable cluster of account-related complaints
Who N26 Is Best For
N26 fits European residents who want everyday banking, budgeting, and card spending in one app, not international shoppers chasing US access.
Why Someone Would Choose N26 Over StatesCard
For a European who wants a genuine bank account with virtual cards attached, N26 is a far more capable financial home than a prepaid US card. But if your specific problem is paying a US service that rejects European cards, N26 does not fix it, and a US-issued option like Halocard does.
What Users Think About These StatesCard Alternatives
Review scores shift constantly, and Trustpilot skews negative because satisfied users rarely post, so read each figure alongside review volume, recency, and what the complaints actually describe. The scores and quotes below were checked against Trustpilot, App Store, and independent review sources in August 2026, and paraphrase real user reviews with short attributed excerpts.
As context for why any of this matters, the US Federal Trade Commission recorded more than 2.3 million fraud reports from consumers in a single recent year, with losses approaching $9 billion, which is precisely the exposure a well-run virtual card is designed to limit.
Halocard
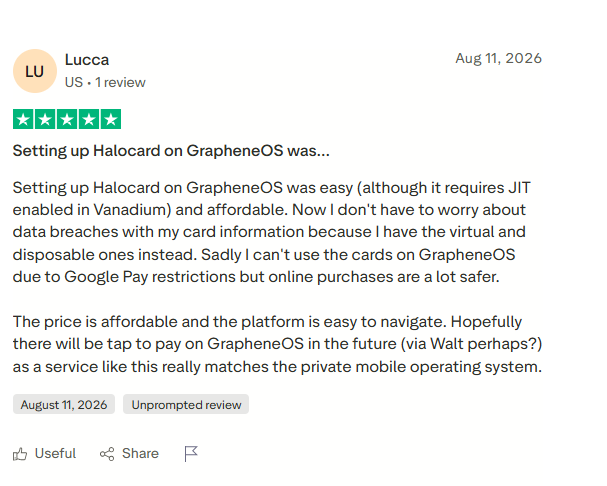
Halocard carries a small but consistently positive Trustpilot presence, rated 4.2/5 (11 reviews), a sample too small to lean on heavily, which we would rather say plainly than dress up. The theme is the product solving a specific problem: reliable access to US-issued virtual Visa cards for non-US users.
Real reviewers describe a smooth setup on the privacy-focused GrapheneOS operating system with no issues encountered and helpful support, and one notes the service is both easy to configure and affordable.
Others cite consistent payment processing and per-card controls, with the occasional mention of early SMS or Apple Pay activation delays that support resolved. The recurring criticism is the subscription model, though several reviewers add that the reliability justifies the monthly fee. Independent trust scanners including Scamadviser and Scam-Detector rate the site as legitimate and low-risk, and Halocard now advertises physical cards as available in addition to its virtual cards.
StatesCard
StatesCard holds a low rating on Trustpilot, at 2.1/5 across 57 reviews, a weak record for a service running this long. The recurring theme is access. Multiple reviewers describe cards that expired or were revoked by the issuing bank with no replacement, leaving loaded balances stranded, and at least one account says the company kept promising a refund it never delivered while stalling with a request to cancel.
A more balanced three-star review reported the card stopped working in late 2024 but that the balance was eventually returned in February. Positive reviews do exist, mostly from long-term streaming users: one describes a decade-old problem finally solved after years of buying expiring Hulu gift cards, and StatesCard's own homepage carries provider-published testimonials from customers in Canada, the UAE, and Iceland paying for Prime and HBO.
A structural limitation worth knowing is that StatesCard is a prepaid debit card, and it openly publishes a support article listing merchants that reject prepaid cards, alongside a policy that blocks money-transfer and cryptocurrency use entirely. Independent scanners rate the domain as legitimate, so this is a fees and reliability problem, not a fraud one.
US Unlocked
US Unlocked sits at 1.9/5 on Trustpilot from 114 reviews, with more than half at one star. The most common recent complaint is an account being placed under review shortly after a first deposit, then remaining restricted while the monthly subscription keeps billing, with one reviewer stating flatly that they could not access their card or funds. Others describe repeated failures to generate a card after loading money, or cards declined at US merchants the site lists as supported.
Even the balanced reviews are pointed: one calls the service functional but says the fees are "simply abusive," while a satisfied Canadian user reports finally being able to watch Hulu after years of US-billing-address rejections (Halocard publishes country-specific guides for markets like Canada and the UK that cover the same problem). A crucial accuracy note for international shoppers is that US Unlocked has been withdrawing load methods for various countries, with support confirming, for example, that it has no funding method for Sweden, so its usefulness outside the US has narrowed over time.
Privacy.com
Privacy.com holds 4.5/5 from 3,358 reviews, with roughly 89% at five stars, the strongest record among the dedicated virtual card providers here. It runs on card-issuing infrastructure from its parent company, Lithic, and reviewers consistently praise the ability to whitelist a merchant on a locked card, set spending caps, and avoid scattering their real card numbers across the web, with one noting they heard about it on the Dave Ramsey show and now set limits to protect against overspending.
The service is also introducing crypto as a payment method, a frequently requested addition. The main negatives are account closures without clear warning, sometimes after an unusual transaction, and slow refunds, since a merchant refund to a closed single-use card can take up to 14 business days to route back or fail outright. For US residents it remains the benchmark for merchant locked cards; for non-US users it is simply unavailable.
RedotPay
RedotPay, a Hong Kong-based crypto card licensed there as a money service operator, has improved to around 3.3/5 on Trustpilot from roughly 1,013 reviews, split about 54% five-star against 33% one-star, alongside a much stronger App Store rating from 2,600-plus ratings.
The card works well for everyday stablecoin spending at Visa merchants, but the recurring complaints are serious. Several reviewers describe declined-transaction fees of $0.50 charged repeatedly even after a card was frozen, with support acknowledging that freezing "cannot prevent merchants from initiating authorization," and one user reported a balance driven negative by a fraudster's repeated attempts.
A widely cited case saw a roughly €697 balance held for 87 days and only released after the customer escalated to Hong Kong authorities. Trustpilot also displays a high-risk-investment notice, reflecting the crypto nature of the platform. The practical takeaway echoes the review consensus: use small amounts and do not park a large balance.
SiraPay
SiraPay's Trustpilot profile had only 3 reviews when we checked in October 2026. The testimonials on its own site come largely from its Product Hunt launch and are positive about onboarding and pricing. Because those are provider-published and the public footprint is small, they carry far less weight than the large independent samples for Revolut, N26, or Privacy.com.
Wise
Wise holds 4.3/5 from 300,000+ reviews. Reviewers value the multi currency balances, transparent fees, and international transfers, with criticism focused on occasional compliance checks, account freezes, and slower support on complex cases.
Revolut
Revolut shows 4.7/5 from 470,000+ reviews, though that figure reflects the consumer app broadly rather than any single feature. Business-relevant feedback praises fast setup, transfers, and multi currency handling, while negatives cluster on account restrictions, freezes, and support quality.
Payoneer
Trustpilot currently withholds a normal Payoneer score, citing a guidelines breach and the removal of fake reviews. The profile still holds tens of thousands of reviews, but Trustpilot's warning means the displayed distribution should not be read as a reliable rating.
Airwallex
Airwallex sits at 2.8/5 from 2,582 reviews, split sharply between strong praise for account managers and multi currency accounts and serious complaints about account terminations and balances held for extended periods.
N26
N26 holds 4.2/5 from 43,100 reviews, with a more polarized distribution than the headline suggests, roughly 63% five-star against 22% one-star. Positive comments focus on the app and digital-banking experience, while negatives raise disputes, account freezes, and fraud-resolution issues.
How to Get Halocard
If you need a StatesCard alternative that reliably reads as a US card at checkout, does not charge 8.5% to load, and works for people outside the United States without an SSN, Halocard is the strongest option on this list.
It issues US-based virtual Visa cards with a custom billing address on every card, supports funding through stablecoins, crypto, cards, and bank transfer, applies per-transaction, daily, and monthly spending limits with instant freeze, and uses 3D Secure authentication.
Because it runs on a loaded balance rather than a linked bank account, there is no credit check and no risk of a card being cut off because a reserve dipped, and your purchases stay separated from your primary account details. Halocard will not give you a full multi currency bank account today, and it does not pay cash back, but for getting a working US card into the hands of someone a foreign card keeps failing, it is purpose-built.
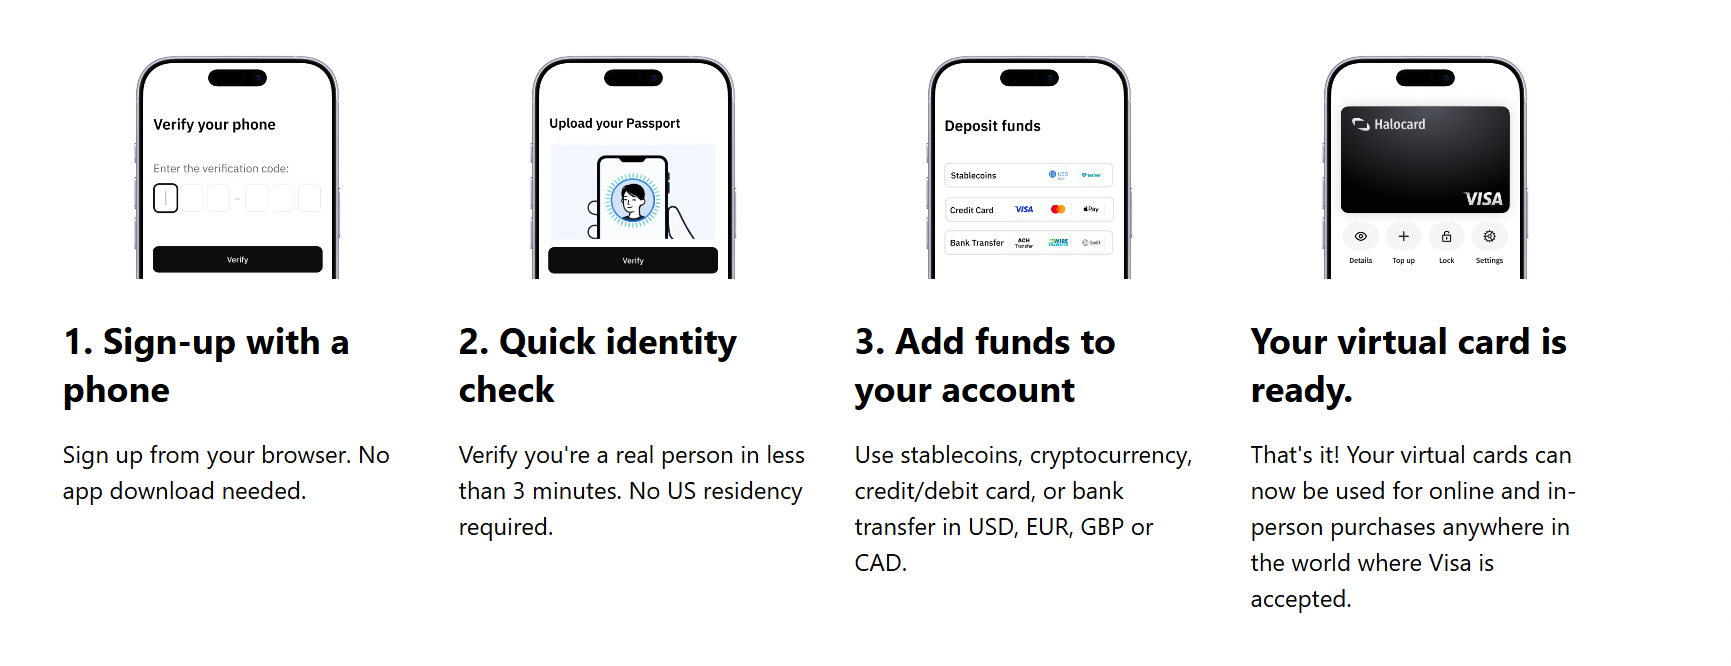
Step-by-Step
-
Create a Halocard account in your browser.
-
Complete identity verification with a passport or national ID, no SSN required for non-US residents.
-
Add funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto, with bank transfers in USD, CAD, EUR or GBP.
-
Create a virtual card, set its billing address and spending limits, and add it to Apple Pay or Google Pay.
-
Start paying US merchants, and freeze or cancel any card instantly when you no longer need it.
Frequently Asked Questions
How Do Virtual Credit Cards Work for International Online Shopping?
Virtual credit cards work by generating a virtual card number, expiration date, and security code that you use for online payments in place of your real card details. They mask your actual banking information, and many providers let you generate a unique card number for each merchant so a leak at one store cannot expose your entire account. A virtual prepaid debit card follows the same logic but is capped at a loaded balance rather than a credit line.
Our full guide on how virtual credit cards work breaks down the authorization flow and card types, and there is a companion walkthrough on how to use a virtual card step by step. Some virtual credit cards are linked to your existing credit card account, while others, like Halocard and most StatesCard alternatives, run on a balance you load yourself. For international shoppers, the key benefit is that a US-issued virtual card can clear US checkouts and bypass regional restrictions that reject a foreign card.
What Is the Best Virtual Card Provider for a US Billing Address?
For a US billing address specifically, Halocard, US Unlocked, and StatesCard are the main contenders, since each issues US-format card details to non-US users. Halocard is the best virtual card provider of the three for reliability and cost, offering a custom billing address on every card, 0% fees on USD online purchases, and acceptance at more than 175 million merchants. US Unlocked is a solid prepaid alternative, while StatesCard's high load fees and weaker reliability make it the fallback rather than the first choice. Our guide to virtual cards with a US billing address explains exactly why address verification trips up foreign cards.
Can I Get a Virtual Prepaid Card Online Without a Credit Check?
Yes. A virtual prepaid card online is funded before you spend, so there is no credit check because your spending is limited to the balance you add. Halocard, US Unlocked, StatesCard, RedotPay, and SiraPay all issue virtual cards without a credit check, and most require only identity verification rather than a bank credit history. This makes prepaid cards a practical payment method for anyone without a US credit file or a US checking account, and our step-by-step guide on how to get a virtual credit card online covers the process for both US and international users.
How Do Merchant Locked Cards and Disposable Cards Help Control Spending?
Merchant locked cards can only be used at the retailer you assign, so if the card number is stolen it is useless anywhere else, which reduces fraud risk and enhances online payment privacy. Disposable cards, sometimes called single-use cards, can be configured to close automatically after one transaction, preventing any further purchases.
Together they are powerful subscription-control tools: you can dedicate one card to a single service, set a spending limit that matches the price, and freeze or cancel it to stop unwanted renewals, an approach we detail in our guide to managing SaaS subscriptions with virtual cards. Privacy.com and US Unlocked lead on merchant-locked cards, while Halocard lets you dedicate a separate card to each merchant or subscription with its own limits, and our overview of masked card services compares the different privacy models.
Which StatesCard Alternatives Let You Load Funds With Crypto or Bank Transfer?
Several, and this is a real point of difference from StatesCard, which explicitly prohibits crypto and money-transfer use in its terms. Users can load funds onto virtual cards using cryptocurrency with Halocard, RedotPay, US Unlocked, and SiraPay, and crypto funding is one of multiple funding methods that can enhance transaction anonymity for international spending.
Halocard funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto, with bank transfers in USD, CAD, EUR or GBP. Loading funds via crypto keeps the deposit off your main bank account, which adds an extra layer of privacy compared with funding directly from a checking account. StatesCard, by contrast, funds only from a credit or debit card, PayPal, or a bank transfer, and recommends pairing the card with a VPN so the checkout's geolocation matches the card's US origin.
Do These Virtual Cards Support Apple Pay and Other Digital Wallets?
Most do. Halocard, RedotPay, Revolut, Wise, Airwallex, and N26 all support Apple Pay and Google Pay, letting you add a digital card to a mobile wallet and pay online or in person. Wise, Revolut, and N26 issue virtual debit cards tied to an account balance, while Halocard issues a virtual Visa credit card, so you can dedicate different cards to different services.
Digital wallets can also enhance online payment privacy and security, since the merchant receives a tokenized number rather than your real card details, which is useful whether you are paying an online service subscription or shopping in a store. StatesCard, by contrast, is oriented around online-only use and does not emphasize mobile-wallet spending.
What Identity Verification Do Virtual Card Providers Require?
Identity verification varies widely. Halocard verifies non-US residents with a passport or national ID in under three minutes and requires no SSN, while US residents provide an SSN or ITIN. Privacy.com requires a US checking account and full KYC.
RedotPay and US Unlocked require identity verification before issuing a card. SiraPay claims a lighter process with no facial verification or government ID, though that should be confirmed for your jurisdiction. In every case, verification is a regulatory step, not a credit check.
Are There Hidden Fees, Monthly Fees, or Inactivity Fees to Watch For?
Always read the full fee schedule, because hidden fees usually live in funding and currency conversion rather than the headline monthly fee. StatesCard charges a $16.99 issuing fee, a $3.95/month fee, and load fees of 7.5% to 8.5%.
US Unlocked adds an unload fee, a balance cap, and additional fees on some funding routes. Some prepaid services also apply inactivity fees on dormant accounts, so check what each service provider charges before you leave a balance sitting.
A good virtual card provider enables users to see every charge upfront rather than burying it in the terms. Halocard keeps this simple with a flat monthly fee and 0% on USD purchases, and it does not charge per-transaction sales fees. Comparing the total cost of adding money and spending, not just the subscription, is the only fair way to judge a virtual card provider.
Can Virtual Cards Manage Subscriptions and Recurring Payments?
Yes, and this is one of their best uses. You can create virtual cards dedicated to individual subscriptions, set spending limits that match each price, and freeze a card to stop a recurring payment or free trial from renewing. Prepaid cards help here too, since a card can only spend its loaded balance, so a forgotten subscription cannot quietly drain your main bank account.
Halocard, Privacy.com, and US Unlocked all support this style of subscription management and spending control. For real-world examples, see our walkthroughs on paying for ChatGPT Plus and paying for Claude with a virtual card, two US-billed subscriptions.
Do Any Alternatives Offer a Real Bank Account or Multi Currency Support?
Yes. If you need a real bank account or multi currency features rather than a single dedicated card, Wise, Revolut, Airwallex, and N26 are the options. Wise and Airwallex hold balances in dozens of currencies with local bank details, Revolut blends account-like banking with disposable cards, and N26 is a licensed European bank. Halocard focuses on card access rather than full banking today, though it includes a US bank account with its own account and routing numbers, so heavy multi currency users may pair it with one of these platforms.
How Do Virtual Cards Protect Financial Data and Reduce Fraud Risk?
Virtual cards protect your financial data by masking your real bank details during online payments, so a merchant or a data breach never exposes your primary account. Disposable cards prevent unauthorized charges after use, merchant-locked cards limit where a number can be spent, and spending limits cap the damage if a card is compromised.
This matters more every year: e-commerce fraud has been growing at roughly 18% globally each year, so the extra layer a virtual card puts between your money and the internet is a meaningful safeguard rather than a novelty. We go deeper on this in our guides to whether virtual credit cards are safe, recovering from a hacked debit card, and checking your digital footprint.
What Is the Best Prepaid Mastercard or Prepaid Visa for Online Purchases?
It depends on where you live and what you are paying for. For international users needing US acceptance, Halocard's virtual Visa is the strongest option, with US Unlocked and StatesCard as prepaid Visa alternatives.
RedotPay offers a stablecoin-funded prepaid card that works internationally, and N26 issues a prepaid-style Mastercard debit within Europe. The best prepaid card for online purchases is the one whose issuing country and funding method match the merchants you actually use, so match the card's origin to your checkout needs. For a broader survey, see our comparison of the best virtual card providers and the ultimate guide to virtual cards.
Can I Set Spending Limits and Track Expenses Across Multiple Accounts?
Yes. Virtual cards let you set specific spending limits per transaction, per day, and per month, which makes managing expenses and staying on budget far easier than a single shared card. Providers like Halocard show every card and transaction in one online account center, filterable by card, so you can track expenses across multiple cards at a glance. If you run multiple accounts or a small team, business tiers add more cards and users, and the dashboard becomes a lightweight budgeting tool as well as a payment method, as covered in our guide to the benefits of virtual debit cards for businesses.
Is StatesCard a Netspend Account or a Real Bank Account?
Neither. StatesCard is not a Netspend account and not a real bank account. It is a virtual prepaid Visa debit card service that issues US card credentials and a US billing address in Delaware, funded by loading money you then spend online. It does not hold deposits like a bank, offer a checking account, or provide the protections of a chartered institution. The same is true of most cards here: Halocard, US Unlocked, and RedotPay are card and payment services rather than banks, while Wise, Revolut, and N26 sit closer to full accounts, with N26 being an actual licensed bank.
Why Do StatesCard Users Look for Alternatives in the First Place?
Most customers start looking for alternatives because of cost or reliability. The load fees of 7.5% to 8.5% make regular top-ups expensive, and the 2.1/5 Trustpilot score reflects repeated complaints about cards being revoked, balances stuck, and slow support. The service still works for basic US streaming, but for anyone spending regularly or relying on the card for important payments, a provider with lower funding fees, more cards, and a stronger track record, such as Halocard, is a safer long-term choice.
Sources
-
Trustpilot. Halocard Reviews.
-
Traders Union. Halocard Review: Is It Safe and Legit?.
-
Scamadviser. Halocard.co Trust Review.
-
Scam Detector. Halocard.co Validator.
-
StatesCard. Virtual US Card & US Billing Address (Homepage).
-
StatesCard. Pricing.
-
StatesCard. Shopping with US Retailers.
-
StatesCard. Pay for US Streaming.
-
StatesCard. Why StatesCard: Prepaid Visa Card for Non-US Residents.
-
StatesCard. Knowledge Base and Support.
-
StatesCard. Merchants or Services That Do Not Accept Pre-Paid Cards.
-
StatesCard. Terms and Conditions.
-
Trustpilot. StatesCard Reviews.
-
Parcel Forward. 9 StatesCard Alternatives for International Shoppers.
-
SecureBlitz. StatesCard Review: Is This Card Worth Your Wallet?.
-
Gridinsoft. StatesCard.com Trust Scan.
-
Reddit. Has anyone tried StatesCard or similar prepaid to bypass geo-blocking? (r/Roadkillshow).
-
US Unlocked. Homepage.
-
US Unlocked. Pricing.
-
US Unlocked. Supported Countries.
-
Trustpilot. US Unlocked Reviews.
-
Reddit. NEVER USE US UNLOCKED (r/internationalshopper).
-
Privacy.com. Virtual Cards (Homepage).
-
Privacy.com. Pricing.
-
Trustpilot. Privacy.com Reviews.
-
All Things Secured. Best Alternatives to Privacy.com for Virtual Credit Cards.
-
US Federal Trade Commission. Consumer Sentinel Network Fraud Data.
-
RedotPay. Homepage.
-
Trustpilot. RedotPay Reviews.
-
Apple App Store. RedotPay: Crypto Card & Pay Ratings & Reviews.
-
Coin Bureau. RedotPay Review 2026.
-
Bleap. RedotPay Review 2026: Fees, Features, Pros & Alternatives.
-
SiraPay. Homepage.
-
SiraPay. Pricing.
-
Wise. Virtual and Physical Card.
-
Wise. Card and Transfer Fees.
-
Trustpilot. Wise Reviews.
-
Revolut. Virtual Cards.
-
Revolut. Plans and Pricing.
-
Trustpilot. Revolut Reviews.
-
Payoneer. Commercial Card.
-
Payoneer. Pricing.
-
Trustpilot. Payoneer Reviews.
-
Airwallex. Corporate Cards.
-
Airwallex. US Pricing.
-
Trustpilot. Airwallex Reviews.
-
N26. Mastercard and Plans.
-
Trustpilot. N26 Reviews.
*Please see Halocard's Terms of Service or Pricing for the most up to date pricing and fee information. This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Halocard LLC or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional. We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.
Halocard Virtual Cards

Instant approval
Create your first card in under 5 minutes.

Private purchases
Purchases never appear on your bank account.

Powered by Visa
Accepted at 175M+ merchants globally.
3 steps to create your virtual credit card
1. Sign up
Create your account from a web browser. No need to download an app.
2. Verify
Verify you're a real person in 3 minutes, from the US or any of 120+ countries.
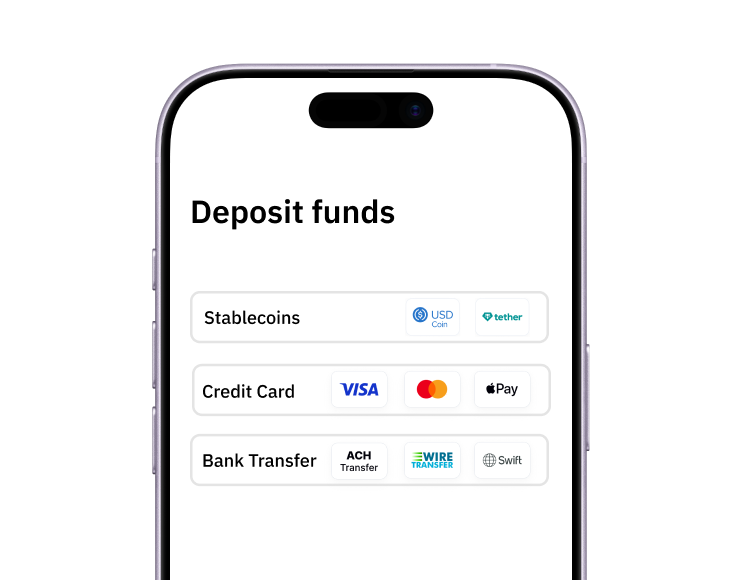
3. Fund
Add funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto.
Pay with Halocard
Pay online and in-person wherever Visa is accepted. You can also order a physical Halocard if you prefer.