The best Ezzocard alternative for most people is Halocard, a reloadable virtual US-issued Visa credit card with 3D Secure, available for customers in the US and 120+ countries with minimal KYC, unlike Ezzocard's single-use cards that often fail checkout checks. For crypto spenders, Vizovcc, RedotPay, and Moon are the closest reloadable options; Privacy.com suits US residents. Your pick depends on whether you need anonymity, reloadable cards, or a US billing address.
If you are searching for the best Ezzocard alternatives, you have hit its core limit: the cards work once, then they are done. Ezzocard is a virtual card service, operating since 2020 by its own account, that sells anonymous prepaid Visa and Mastercard cards funded with cryptocurrency, no KYC, no ID, no bank account, and no personal documents. For a quick, private one-off purchase, whether online shopping, buying Google Ads, or registering a domain, it delivers card details by email in minutes, although its original site ezzocard.com went offline in August 2025 and its pages now sit at ezzocard.finance.
Three problems push users elsewhere. Ezzocard cards are non reloadable and single-use, so every purchase means a new card and another card issuance fee. Only its Gold card supports 3D Secure, so its other cards can be declined at PayPal accounts, Apple, Google Play, and streaming platforms. And the real costs are steep: every card is priced above its face value, by an amount that varies by card (a $100 Gold card was $125.00 on 2026-10-12), and its pages disclose no foreign-currency fee for its USD cards. Ezzocard says it delivers anonymity at a premium, but this guide compares 17 virtual card and payment solutions that do the same jobs with reloadable cards, 3DS support, and lower fees.
Key Takeaways
-
Halocard is the best all-round Ezzocard alternative. A reloadable US-issued Visa credit card with 3D Secure support, available for customers in the US and 120+ countries with minimal KYC, 0% fees on USD online purchases, and a custom billing address on every card.
-
Match the alternative to your priority. Vizovcc, RedotPay, Moon, and Buvei are crypto-funded options that add reloadable cards and 3DS, Privacy.com and StatesCard suit US-billing needs, and Wise, Revolut, or N26 cover multi-currency banking.
-
Reloadable beats single-use for anything recurring. Ezzocard cards cannot handle ongoing subscriptions because they run out; a reloadable card with recurring billing support is the fix.
-
Watch the real costs and the clone sites. Ezzocard prices every card above its face value, and it has many fraudulent mirror sites, so anonymity is not the only thing to weigh.
-
Ezzocard is narrow, and its site has moved. It is a single-purpose privacy tool, yet the stronger options below do more for less across most use cases.
Quick Comparison Table
| Provider | Card / Account Type | Availability | Reloadable / 3DS | Key Pricing and Fees | Best For |
|---|---|---|---|---|---|
| Halocard | US-issued Visa credit card | US and 120+ countries; minimal KYC | Reloadable; 3DS | $12–$75/mo; 1.5% + $0.30 non-USD FX | Reliable US virtual card with 3DS |
| Vizovcc | Crypto-funded virtual Visa/Mastercard | Broad international | Reloadable; 3DS | $5–$15 issuance; no monthly fee | Reloadable, 3DS-passing crypto cards |
| StatesCard | US virtual prepaid Visa debit | International; Delaware address | Reloadable; limited 3DS | $16.99 sign-up, $3.95/month; loads 5% to 8.5% | Basic US streaming and shopping |
| US Unlocked | US virtual prepaid cards | International (supported countries) | Reloadable; 3DS | $4.95/month; loads 2% to 5% + $1 | Shopping US stores from abroad |
| Privacy.com | US virtual payment cards | US residents, 18+, US bank | Merchant-locked/one-time | $0–$25/mo; 3% FX on lower tiers | US residents wanting locked cards |
| RedotPay | Stablecoin-funded virtual/physical card | Reported 100+ countries | Reloadable; 3DS | $10 virtual; $100 physical; Pro $12.90/mo | Crypto and stablecoin spenders |
| Moon | Crypto-funded Visa prepaid card | Global (X) / US (1X) | X reloadable; 3DS varies | First X card free, $2.99 extra; 1% per tx | Spending Bitcoin and stablecoins |
| SiraPay | Privacy-focused virtual card | Claims 150+ countries | Reloadable; varies | Free plan; $0.99/mo or $4.99/yr | Low-cost private cards |
| MySudo | Privacy suite + virtual cards | US card users | Reusable; US merchants | Paid plans $1.99–$14.99/mo | Bundled privacy with cards |
| Payz (ecoPayz) | E-wallet + virtual/physical Mastercard | 170+ countries | Reloadable e-wallet | ~€1.80 card issue; ~4% card fee | Multi-currency e-wallet |
| Wise | Multi-currency account + debit card | Broad international | Reloadable; 3DS | No monthly fee; card ~$9; mid-market FX | Cheap cross-border spend |
| Revolut | Multi-currency account + virtual/disposable debit | UK, EEA, US, more | Reloadable; disposable option | $0–$16.99/mo | Multi-currency and disposable cards |
| Payoneer | Business account + Mastercard | Broad international; business | Reloadable | $29.95/yr card fee; up to 3.5% conversion | Cross-border business earnings |
| Airwallex | Business account + Visa cards | Businesses in 69 countries | Reloadable; 3DS | Explore $0; user fees on higher tiers | Multi-currency business spend |
| N26 | European bank + Mastercard debit | European markets | Reloadable; 3DS | Free to €16.90/mo | European digital banking |
| Buvei | Crypto-funded virtual card app | Global (app) | Reloadable | Opaque pricing | Crypto card app users |
| DoNotPay | Free-trial virtual card | US-focused | Non-charging | Part of a subscription app | Dodging free-trial charges |
Best Ezzocard Alternatives for Virtual Cards and Anonymous Online Payments
Below are the 17 best alternatives to Ezzocard, starting with the option that fixes its biggest weaknesses, then moving through crypto-funded rivals, US-billing specialists, and multi-currency accounts.
1. Halocard
Halocard is a US-based fintech offering reloadable virtual and physical payment cards built around a US-issued virtual Visa that behaves like a domestic card at checkout. Where Ezzocard sells you a throwaway card that supports 3D Secure only on its Gold card, Halocard gives you reloadable cards with full 3DS support, so subscriptions renew instead of breaking.
How It Works. You sign up in a browser and verify with a passport or national ID in under three minutes, no SSN for non-US residents, then generate virtual cards with their own limits and billing address. Cards are issued through financial partners under Visa and run at 175 million-plus merchants via Apple Pay and Google Pay.
Costs & Fees.
-
Plans: Essential $12/mo (3 cards), Pro $15/mo (12), Elite $75/mo (60); business from $29/mo
-
0% on USD online purchases; 1.5% + $0.30 non-USD
-
Funding: debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto
Spending Limits and Funding. Halocard runs on money you deposit rather than a credit line, with no credit check. You can add funds by cryptocurrency, card, or bank transfer, and set per-transaction, daily, and monthly limits with instant freeze on each card.
Key Advantages.
-
Reloadable cards with 3D Secure support, so recurring billing works
-
Available for customers in the US and 120+ countries with minimal KYC, no SSN for non-US residents
-
A custom billing address on every card, clearing most US merchant checks
Specific Drawbacks.
-
A subscription rather than pay-per-card, and no permanent free plan
-
No cash back, accounting integrations, or bill pay
-
1.5% + $0.30 FX outside USD
Who It's Best For. International shoppers, media buyers, and privacy-focused users who need a reliable, reloadable US card, as covered in our guide to virtual cards with a US billing address.
Why Someone Would Choose Halocard Over Ezzocard. Where Ezzocard forces a new single-use card and a fresh fee for every purchase, Halocard reloads, passes 3DS, and costs 0% on USD spend, so it works for ongoing subscriptions Ezzocard cannot serve. Our full Ezzocard vs Halocard comparison lays it out.
2. Vizovcc
Vizovcc positions itself directly as an Ezzocard alternative, selling crypto-funded virtual Visa and Mastercard cards that are reloadable and pass 3D Secure, which is exactly where Ezzocard struggles.
How It Works. You buy a card with cryptocurrency and receive details instantly, then reuse and top it up rather than discarding it. Because its cards clear 3DS, they link reliably to PayPal accounts and work where Ezzocard is rejected.
Costs & Fees.
-
Flat issuance of $5 to $15 per card
-
No monthly fee and no hidden top-up percentages
-
Crypto funding
Spending Limits and Funding. Cards are reloadable and support recurring billing, so a subscription can renew on the same card. Funding is crypto-based, with pricing shown upfront.
Key Advantages.
-
Reloadable cards with 3D Secure, unusual among crypto-funded providers
-
Recurring billing support for subscriptions
-
Low, flat issuance fees and no monthly charge
Specific Drawbacks.
-
Crypto-only funding
-
A smaller, newer brand with a thin public review record
-
No US bank-grade protections
Who It's Best For. Crypto users who want Ezzocard-style privacy but with reloadable cards, 3DS, and subscription support.
Why Someone Would Choose Vizovcc Over Ezzocard. It fixes Ezzocard's two biggest flaws, the non-reloadable design and 3DS failures, at a similar or lower cost, making it the closest like-for-like upgrade for crypto spenders.
3. StatesCard
StatesCard is a virtual prepaid Visa debit card that hands international users US card details and a Delaware billing address for streaming, app stores, and US shopping.
How It Works. You sign up, often in minutes, load funds, and generate a US card with an open-to-buy, store-locked, or one-time option, each carrying a US billing address to clear address checks.
Costs & Fees.
-
$16.99 one-time issuing fee; $3.95/month
-
Load fees: card 7.5% + $0.30, PayPal 8.5% + $0.30, bank transfer 5% + $0.30
-
No per-transaction sales fee
Spending Limits and Funding. Prepaid, so you spend what you load, via card, PayPal, or bank transfer; crypto is barred.
Key Advantages.
-
A clean US billing address in Delaware
-
Store-locked and one-time cards
Specific Drawbacks.
-
The steepest load fees here, up to 8.5%
-
No crypto funding
-
A low Trustpilot score with stuck-balance complaints
Who It's Best For. Non-US users wanting the simplest route to basic US streaming who accept a premium to load.
Why Someone Would Choose StatesCard Over Ezzocard. StatesCard cards reload and hold a US billing address, so unlike Ezzocard they can carry ongoing subscriptions, though at higher load fees. See our StatesCard vs Halocard comparison.
4. US Unlocked
US Unlocked issues US virtual prepaid cards with a US billing and shipping address for shopping American online stores from abroad.
How It Works. You verify, load a USD wallet, and create everyday, store-locked, or one-time cards with their own card number and security code.
Costs & Fees.
-
$4.95/month or $39.95/year
-
Load fees from 2% to 5% + $1; balance capped near $3,000
-
No transaction fee on spending
Spending Limits and Funding. Prepaid, funded by crypto, card, Apple Pay or Google Pay, and bank transfers such as SEPA and UK Faster Payments.
Key Advantages.
-
Merchant-locked and one-time cards
-
Crypto funding and 3D Secure
Specific Drawbacks.
-
Load fees plus fixed charges add up
-
Account-review complaints while billing continues
-
A low Trustpilot score
Who It's Best For. International shoppers wanting US store access with merchant-locked control.
Why Someone Would Choose US Unlocked Over Ezzocard. Reloadable cards, a US billing address, and 3DS make it far better for recurring US purchases than Ezzocard's single-use model. Our US Unlocked vs Halocard comparison goes further.
5. Privacy.com
Privacy.com is the mature US name in virtual payment cards, built to isolate each purchase from your bank, with merchant-locked and single-use cards.
How It Works. Available to US residents 18-plus who link a US checking account, it creates cards that lock to one merchant or close after a single use, with a browser extension to autofill details.
Costs & Fees.
-
Personal free (12 cards/month); Plus $5, Pro $10, Premium $25
-
3% FX on the free and Plus tiers; 0% and 1% cash back on Pro and Premium
Spending Limits and Funding. Cards draw from your linked US checking account, so this is not a loaded prepaid balance.
Key Advantages.
-
A strong free tier for US residents
-
Merchant-locked and one-time cards
Specific Drawbacks.
-
US-only, requiring a US bank, which rules out most Ezzocard users
-
KYC required
-
No multi-currency features
Who It's Best For. US residents wanting per-merchant card control over subscriptions and online purchases.
Why Someone Would Choose Privacy.com Over Ezzocard. For US residents it offers merchant-locked cards free and with far better reliability, though it cannot serve non-US users the way Ezzocard's no-KYC model does. See our best Privacy.com alternatives roundup.
6. RedotPay
RedotPay is a Hong Kong-based crypto and stablecoin card platform reporting more than 8 million users and acceptance at over 130 million merchants.
How It Works. You verify, fund a balance with crypto or stablecoins, and issue a reloadable virtual or physical card that links to Apple Pay, Google Pay, or PayPal.
Costs & Fees.
-
$10 virtual card; $100 physical; optional Pro $12.90/month
-
Cash back on qualifying mobile-wallet spend; some merchants carry a 1.5% fee
Spending Limits and Funding. Crypto and stablecoin funding, with limits by tier and verification level.
Key Advantages.
-
Reloadable card with 3D Secure and mobile wallets
-
Stablecoin funding for international spending
Specific Drawbacks.
-
A non-US BIN and identity verification required
-
Declined-transaction fees and account-freeze complaints
-
A Trustpilot high-risk-investment flag
Who It's Best For. Crypto holders who want a reloadable card rather than Ezzocard's single-use one.
Why Someone Would Choose RedotPay Over Ezzocard. It reloads, passes 3DS, and supports mobile wallets, so it handles recurring spend Ezzocard cannot, as our RedotPay vs Halocard comparison explains.
7. Moon
Moon (Pay with Moon) sells Visa prepaid cards funded with Bitcoin, Lightning, and stablecoins, aimed at spending crypto with low fees across millions of merchants.
How It Works. You fund with crypto and issue a reloadable Moon X Card for global use or a disposable Moon 1X Card for US merchants, both digital and instant.
Costs & Fees.
-
Moon X: first card free, extra cards $2.99, 1% per transaction, no FX fee
-
Moon 1X: $1.49 issuance, 0% transaction fee
-
No load or top-up fees; account-wide spend cap around $4,000/month
Spending Limits and Funding. Bitcoin, Lightning, USDC, and USDT funding, with exchange rates passed from wholesale providers.
Key Advantages.
-
Reloadable global card and low, transparent fees
-
No load fees and competitive FX
Specific Drawbacks.
-
As of early 2026, a high volume of reports allege the platform has gone offline or refused refunds
-
Account restrictions surface in recent reviews
-
Crypto-only, with a monthly spend cap
Who It's Best For. Bitcoin and stablecoin holders wanting low-fee card spend, who test small first given recent reliability reports.
Why Someone Would Choose Moon Over Ezzocard. Moon's reloadable card and near-zero load fees undercut Ezzocard's costs sharply, though its recent reliability complaints mean caution on both sides.
8. SiraPay
SiraPay is a newer privacy-focused virtual card service aimed at freelancers, crypto users, and digital nomads who want minimal onboarding.
How It Works. It advertises onboarding with no facial verification or government ID and lets you create up to five virtual cards, with claimed coverage across 150-plus countries.
Costs & Fees.
-
A free-forever plan, plus $0.99/month or $4.99/year card options
-
Funding currently via Binance Pay (USDT)
Spending Limits and Funding. Crypto-native, with funding options the company says will expand.
Key Advantages.
-
Very low pricing and light onboarding
-
Up to five virtual cards
Specific Drawbacks.
-
A short track record and thin transparency
-
Narrow current funding options
-
Claims worth verifying for your region
Who It's Best For. Cost-sensitive users who want a private card and can accept a young service.
Why Someone Would Choose SiraPay Over Ezzocard. Its $0.99 card and reusable model beat Ezzocard's per-card fees, though it is newer and less proven.
9. MySudo
MySudo bundles virtual cards into a broader privacy suite of masked phone numbers, emails, and browsers from Anonyome Labs.
How It Works. Each identity, or "Sudo," gets its own number, email, and one virtual Mastercard that routes to a linked US funding card, so purchases show a neutral descriptor.
Costs & Fees.
-
Paid plans from about $1.99 to $14.99/month; the free tier excludes cards
-
A processor fee of roughly 2.99% + $0.31 per approved purchase, with a $0.50 minimum
Spending Limits and Funding. Account-wide caps around $250 per purchase and $350 per day, funded by one linked US credit or debit card, US merchants only.
Key Advantages.
-
Cards bundled with private numbers and inboxes
-
A neutral statement descriptor
Specific Drawbacks.
-
US users and US merchants only, no international acceptance
-
Low purchase caps and a per-transaction processor fee
-
No US billing-address control
Who It's Best For. US users who want a full privacy toolkit with a low-value card attached.
Why Someone Would Choose MySudo Over Ezzocard. It pairs cards with genuine identity privacy and reusable use, though its US-only reach is narrower than Ezzocard's global model.
10. Payz (formerly ecoPayz)
Payz is a long-running, FCA-regulated e-wallet from PSI-Pay in the UK, offering a virtual prepaid Mastercard and, for higher tiers, a physical card, across 170-plus countries.
How It Works. You open and verify an account, load funds, and use the virtual card for online payments, with a tiered VIP program that lowers fees as activity grows.
Costs & Fees.
-
A virtual card issue fee around €1.80
-
Around a 4% fee on virtual card transactions
-
Physical card reserved for VIP tiers
Spending Limits and Funding. Balances and limits scale with VIP tier; funded by bank transfer, card, and crypto.
Key Advantages.
-
A long, regulated track record and strong support reputation
-
40-plus currencies and one-time virtual cards
Specific Drawbacks.
-
A roughly 4% card fee is high for everyday shopping
-
No US billing address
-
Oriented to gambling and trading
Who It's Best For. Users wanting an established multi-currency e-wallet, especially for gaming and trading deposits.
Why Someone Would Choose Payz Over Ezzocard. It is far more established and reloadable, though its 4% card fee and lack of a US profile make it a different tool than Ezzocard's one-off cards.
11. Wise
Wise, formerly TransferWise, is a multi-currency account with virtual and physical debit cards, known for transparent transfers at the mid-market rate.
How It Works. You open an account, hold 40+ currencies with local bank details, and issue reloadable virtual and physical cards that spend in 160-plus countries.
Costs & Fees.
-
No monthly fee; one-time opening fee around €50 in the EEA
-
Physical card from roughly $9; virtual cards generally free
-
Transfer fees around 0.33% to 1.0%
Spending Limits and Funding. A balance model, funded from your currencies, with auto-conversion at spend time.
Key Advantages.
-
No monthly fee and transparent pricing
-
Mid-market rates and 40+ currencies
Specific Drawbacks.
-
Not a US-issued card, so weaker on US address checks
-
No rewards or subscription controls
-
Some ATM and conversion fees
Who It's Best For. International users wanting cheap cross-border spend rather than anonymity.
Why Someone Would Choose Wise Over Ezzocard. Wise reloads, passes 3DS, and costs far less to run, though without Ezzocard's no-KYC anonymity. See our Revolut vs Wise vs Halocard comparison.
12. Revolut
Revolut blends transfers, currency exchange, budgeting, and both regular and disposable virtual cards in one app.
How It Works. You create up to 20 reloadable virtual cards, plus a single-use disposable card whose details refresh after each purchase, all managed in-app.
Costs & Fees.
-
Standard $0/month; Premium $9.99; Metal $16.99
-
Card funding up to 1% to 3%; FX free to a monthly allowance, then a small fee
Spending Limits and Funding. Spends from your available balance across currencies.
Key Advantages.
-
A free tier with up to 20 virtual cards
-
A disposable single-use card
Specific Drawbacks.
-
Features and pricing vary by country
-
Not built to give non-US users a US card
-
Disposable cards cannot run subscriptions
Who It's Best For. Travelers and internationally active users wanting disposable and multi-currency cards.
Why Someone Would Choose Revolut Over Ezzocard. It offers reloadable and disposable cards free, though like Wise it neither solves US billing nor matches Ezzocard's anonymity.
13. Payoneer
Payoneer is a business-focused cross-border payments platform for freelancers, sellers, and companies receiving international payments.
How It Works. Eligible customers issue many reloadable virtual cards that spend from balances in USD, EUR, GBP, CAD, or JPY.
Costs & Fees.
-
$29.95 annual card fee; additional virtual cards free
-
Up to 1.8% without conversion, up to 3.5% with conversion
Spending Limits and Funding. High approved limits funded by incoming business payments; not issued to Russia or India.
Key Advantages.
-
Business accounts for cross-border earnings
-
Many free additional virtual cards
Specific Drawbacks.
-
Business use only
-
Annual card and possible account fees
-
A Trustpilot guidelines-breach notice
Who It's Best For. Businesses already paid by international clients who want to spend those balances.
Why Someone Would Choose Payoneer Over Ezzocard. For business revenue, its reloadable cards beat one-off anonymous cards, though it is far heavier for a single private purchase.
14. Airwallex
Airwallex is a global business platform with multi-currency accounts, low-markup FX, and reloadable Visa corporate cards.
How It Works. Businesses open Global Accounts in 20-plus currencies and issue unlimited virtual or physical corporate cards with spending controls.
Costs & Fees.
-
Explore free in the US, conditional elsewhere; Grow around $12 per user
-
FX markup 0.5% to 1.0%
Spending Limits and Funding. Per-card and per-wallet limits funded from multi-currency balances.
Key Advantages.
-
Low FX and multi-currency accounts
-
Genuinely global with no US-entity requirement
Specific Drawbacks.
-
Built for businesses, not private shoppers
-
Free access outside the US is conditional
-
Account-review complaints in places
Who It's Best For. Cross-border companies needing multi-currency accounts and cards together.
Why Someone Would Choose Airwallex Over Ezzocard. For a business it replaces a stack of tools, but it is overkill for the one-off anonymous purchase that is Ezzocard's niche.
15. N26
N26 is a licensed European digital bank offering virtual and physical Mastercard debit cards.
How It Works. N26 Standard includes one free virtual Mastercard after a one-time €10 activation, with up to six active virtual cards across plans.
Costs & Fees.
-
Standard free; Smart €4.90; Go €9.90; Metal €16.90
-
Non-euro ATM fees on lower tiers
Spending Limits and Funding. Cards spend from your N26 balance, with Spaces sub-accounts for budgeting.
Key Advantages.
-
A full European bank account with deposit protection
-
A free virtual card and broad mobile-wallet support
Specific Drawbacks.
-
European markets only
-
No US billing address
-
Account-freeze complaints in reviews
Who It's Best For. European residents wanting real banking with virtual cards.
Why Someone Would Choose N26 Over Ezzocard. For Europeans it is a full bank, not a disposable card, but it does nothing for US access or anonymity.
16. Buvei
Buvei is a crypto-funded virtual card app aimed at users who want to spend digital assets through a card, sitting in the same niche as Ezzocard.
How It Works. You fund with crypto in-app and generate a reloadable virtual card for online payments, with pricing shown at purchase.
Costs & Fees.
-
Pricing is not clearly published upfront
-
Crypto funding
Spending Limits and Funding. Crypto-based, with limits set in-app.
Key Advantages.
-
Reloadable crypto-funded cards
-
App-based management
Specific Drawbacks.
-
Opaque pricing and a low App Store rating
-
A thin public track record
-
Limited support signals
Who It's Best For. Crypto users comfortable with a young app who want reloadable cards.
Why Someone Would Choose Buvei Over Ezzocard. Buvei reloads where Ezzocard does not, though its opaque pricing and low ratings mean testing small first, as our Buvei vs Halocard comparison discusses alongside similar options.
17. DoNotPay
DoNotPay is a US consumer-help app whose Free Trial Card is a narrow tool: a virtual card that signs up for free trials and then declines any real charge.
How It Works. It generates a card number, expiration date, and security code not linked to any balance, so when a trial ends the follow-up charge is declined. It includes a US billing address.
Costs & Fees.
-
Part of DoNotPay's subscription app, with no load fees
-
Cannot be used for real purchases
Spending Limits and Funding. Nothing to fund, since the card holds no money by design.
Key Advantages.
-
Purpose-built to stop charges after free trials
-
A US billing address for US-restricted trials
Specific Drawbacks.
-
Free trials only, not real spending
-
Tied to a broader app
-
Regulatory scrutiny over some marketing claims
Who It's Best For. People who mainly want to test free trials without an unwanted charge.
Why Someone Would Choose DoNotPay Over Ezzocard. For free trials it needs no crypto or fees, but it cannot buy anything, so it complements rather than replaces a real card.
What Users Think About These Ezzocard Alternatives
Review scores move constantly and Trustpilot skews negative, so weigh each figure against volume, recency, and what the complaints describe. Scores below were checked against Trustpilot, the App Store, and independent sources and paraphrase real reviews. For context, the US Federal Trade Commission logged more than 2.3 million fraud reports in a single recent year, with losses near $9 billion, exactly the risk a well-run virtual card is meant to shrink.
Ezzocard
Ezzocard's public reputation is mixed and depends heavily on which snapshot you read: recent independent tracking puts it around 2.5/5 on Trustpilot across 368 reviews, flagged as possibly linked to high-risk investments, with refund denials and unresponsive support the loudest complaints, while some review sites report a softer 3.7 with praise for instant delivery and crypto payments.
Across those reviews, the virtual Ezzocard cards draw consistent criticism on three points: high fees, occasional non-delivery, and cards declined at 3D Secure merchants, with the Visa and Mastercard options performing differently by store. A crucial, often-missed safety point: Ezzocard virtual cards are widely cloned, so users must verify the official domain before paying, since fraudulent mirror sites can steal funds outright.
Halocard
Halocard holds a small but positive Trustpilot presence, around 4.2/5 (11 reviews), too small to lean on heavily. Reviewers describe a smooth setup on the privacy-focused GrapheneOS operating system with helpful support, and steady payment approval with per-card controls; the recurring gripe is the subscription model, which several say the reliability justifies. Independent scanners rate the site legitimate, and it now offers physical cards alongside virtual ones.
Vizovcc
As a newer, niche brand, Vizovcc has a thin public review footprint, so judge it on its clearly stated features, reloadable crypto cards with 3DS and recurring billing, rather than a large sample, and test with a small amount first.
StatesCard
StatesCard sits near 2.1/5 from 57 reviews, with revoked-card and stranded-balance complaints the recurring theme, balanced by long-term streaming users who report years of trouble-free use.
US Unlocked
US Unlocked lands around 1.9/5 from 114 reviews, with accounts frozen while the monthly fee keeps billing the most common complaint, and withdrawn load methods for several countries a real accuracy note.
Privacy.com
Privacy.com holds 4.5/5 from 3,358 reviews, praised for merchant-locked cards and spending caps, though flagged for account closures without warning and slow refunds.
RedotPay
RedotPay has climbed to about 3.3/5 from roughly 1,013 reviews, plus a stronger App Store rating, but declined-transaction fees charged after a card is frozen and long refund sagas recur.
Moon
Moon draws serious recent concern, with many early-2026 reports of the platform going offline or refusing refunds and account-restriction complaints on its Trustpilot page, so treat it as higher risk and spend small.
SiraPay
SiraPay's Trustpilot profile had only 3 reviews when we checked in October 2026, so it and the on-site testimonials, drawn largely from its Product Hunt launch, carry limited weight against the larger samples here.
MySudo
MySudo sits around 3.1/5 on a very small Trustpilot sample, with praise for its privacy bundle and complaints about refunds and app friction rather than the cards themselves.
Payz
Payz has a long, regulated history and a solid support reputation, with card and crypto deposits generally working and transfer fees the main gripe; complaints tend to involve verification and withdrawal timing.
Wise
Wise holds 4.3/5 from 300,000+ reviews, valued for transparent fees and multi-currency balances, with occasional compliance checks and account freezes the main negatives.
Revolut
Revolut shows 4.7/5 from 470,000+ reviews, though that figure reflects the consumer app broadly; feedback praises fast transfers and multi-currency handling while flagging account restrictions and support quality.
Payoneer
Trustpilot currently withholds a normal Payoneer score, citing a guidelines breach and the removal of fake reviews, so its tens of thousands of reviews should not be read as a reliable rating.
Airwallex
Airwallex sits at 2.8/5 from 2,582 reviews, split between praise for account managers and multi-currency accounts and serious complaints about account terminations and held funds.
N26
N26 holds 4.2/5 from 43,100 reviews, more polarized than the headline suggests, with the app and digital-banking experience praised and account freezes and dispute handling the main criticisms.
Buvei
Buvei has a thin, weak review footprint and a low App Store rating typical of young crypto card apps, so treat it as spend-small until it proves itself.
DoNotPay
DoNotPay's Free Trial Card earns praise for one thing, stopping charges after a trial, though the wider app has faced regulatory scrutiny over broader "robot lawyer" marketing claims.
How to Get Halocard
If you want an Ezzocard alternative that reloads, passes 3D Secure, and works for customers in the US and 120+ countries with minimal KYC, Halocard is the strongest option here.
It issues reloadable US-based virtual Visa cards with a custom billing address on every card, supports funding by stablecoins, crypto, cards, and bank transfer, applies per-transaction, daily, and monthly limits with instant freeze, and uses 3D Secure by Visa. Because it runs on a loaded balance rather than a credit line, there is no credit check, and your purchases stay separated from your primary account details. Unlike Ezzocard's single-use cards, a Halocard reloads and carries recurring subscriptions without breaking.
For related reading, see the best virtual card providers, the ultimate guide to virtual cards, and our Ezzocard vs Halocard comparison. You can also learn more about the cards and how Halocard handles your privacy.
Step-by-Step
-
Open a Halocard account in a browser.
-
Verify with a passport or national ID; no SSN is required for non-US residents.
-
Add funds using stablecoins, crypto, a card, or a SEPA or UK Faster Payments transfer.
-
Generate a virtual card, set its billing address and limits, and add it to Apple Pay or Google Pay.
-
Pay online merchants, and reload or freeze any card whenever you need to.
Frequently Asked Questions
What Are the Best Ezzocard Alternatives for Reloadable Virtual Cards?
For reloadable cards, Halocard leads: a US-issued virtual Visa with 3D Secure that tops up rather than expiring at the end of a short card period. Vizovcc, RedotPay, Moon, and Buvei are crypto-funded reloadable options, while Wise, Revolut, and N26 offer reloadable cards tied to a bank account. Ezzocard cards, by contrast, are non-reloadable and single-use, so you must purchase virtual prepaid cards anew for every set of online transactions. Our roundup of the best virtual card providers ranks the wider market.
How Do Prepaid Cards and a Virtual Card Service Handle 3D Secure?
3D Secure is the extra checkout verification many merchants now require, and only Ezzocard's Gold card supports it. A modern virtual card service like Halocard, RedotPay, or Vizovcc builds in 3DS support, so payments at PayPal, Apple, Google Play, and streaming sites go through. Confirm 3DS support directly, since a card that cannot pass it is declined at a growing share of online stores. Our guide on how virtual credit cards work covers the authorization flow.
Can I Get a Virtual Card Without a Bank Account or KYC?
Yes, though the trade-offs differ. Ezzocard offers anonymous prepaid cards with no KYC and no bank account, funded by crypto, across over 130 countries. Halocard needs only minimal KYC and no bank account across 120+ countries, adding reloadable cards and 3DS that no-KYC single-use cards lack. KYC requirements vary widely, so weigh anonymity against reliability, acceptance, and cost. Our walkthrough on how to get a virtual credit card online explains the options.
What Are the Real Costs of Ezzocard Compared With the Alternatives?
Ezzocard's real costs run high: each card is priced above its face value by an amount that varies by card (a $100 Gold card was $125.00 on 2026-10-12), with a limited validity period and, under its terms, no refunds, although its homepage promises 90% back on unused cards. Its pages disclose no foreign-currency fee for its USD cards, and its CAD cards charge 2.5% outside Canadian dollars. Because the cards are single-use, those fees repeat on every purchase, and its pricing structure is built around anonymity rather than value. Reloadable alternatives spread cost across many transactions and let you hold multiple cards: Halocard charges a flat monthly fee with 0% on USD spend, Moon charges about 1% per transaction with no load fees, while Vizovcc uses flat $5 to $15 issuance. Since these cards accept Mastercard or Visa and support worldwide shopping, a reloadable card is almost always cheaper for frequent use.
Which Payment Methods and Ezzocard Alternatives Accept Cryptocurrency to Add Funds?
Plenty. You can add funds with cryptocurrency at Halocard, Vizovcc, RedotPay, Moon, SiraPay, and Buvei, and Ezzocard itself supports Bitcoin, Ethereum, and USDT among its payment methods. Crypto-funded alternatives tend to focus on privacy and low KYC, which is what draws Ezzocard's audience in the first place, since they collect little identity data. The difference is that these alternatives pair crypto funding with reloadable cards, mobile wallets, and 3D Secure, so the card keeps working after the first card is spent. Our guide to masked card services breaks down how each privacy model works.
Do These Payment Solutions Support Apple Pay and Recurring Subscriptions?
Many do. Halocard, RedotPay, Wise, Revolut, and N26 support Apple Pay and Google Pay and, being reloadable, can carry recurring subscriptions across streaming, ad platforms, or SaaS tools. Ezzocard cards generally cannot, since they run out of balance and are not reloadable, so every renewal fails. See our walkthroughs on paying for ChatGPT Plus and paying for Claude with a virtual card.
What Is the Best Prepaid Visa or Credit Card for a US Billing Address?
For a US billing address, Halocard, StatesCard, and US Unlocked issue US-format cards to non-US users, with Halocard the most reliable thanks to a custom billing address on every card and 3DS support. Ezzocard can register cards to US or Canadian billing addresses too, but its single-use design and 3DS failures make it weaker for anything ongoing. Our guide to virtual cards with a US billing address explains why address matching decides so many US checkouts.
How Do Virtual Cards Protect Online Privacy and Reduce Fraud Risk?
Virtual cards mask your real card and bank details at checkout, so a merchant breach exposes a disposable number rather than your primary account. Merchant-locked cards limit a stolen number to one vendor, one-time cards close after a single transaction, and spending limits cap any loss. This is why privacy-focused virtual cards, whether anonymous like Ezzocard or reloadable like Halocard, remain popular as e-commerce fraud climbs. See our guide on whether virtual credit cards are safe.
Can Ezzocard Cards or a Gift Card Handle Recurring Subscriptions?
No, and this is the crux. Ezzocard cards are single-use with a fixed card balance, so they cannot carry recurring payments; when the balance runs out mid-subscription, the next charge is declined. A prepaid gift card has the same flaw, since it also cannot reload. The real advantage of a reloadable virtual card is that it holds multiple currencies or tops up on demand, so worldwide payments and ongoing subscriptions keep flowing on one card number. Halocard, RedotPay, and Vizovcc all support this where Ezzocard cards and a gift card cannot.
Is Ezzocard Safe and Legit, and Why Do Users Seek Alternatives?
Ezzocard says it has sold anonymous single-use cards since 2020, but it names no company or licence, and its original site ezzocard.com went offline in August 2025; its pages now sit at ezzocard.finance. Users seek alternatives mainly because the cards are non-reloadable, only the Gold card supports 3D Secure, and they carry high per-card fees, and because Ezzocard has many fraudulent clone sites that make buying safely trickier. For anyone who needs a reloadable card, subscription support, or lower ongoing costs, a provider like Halocard is the safer long-term choice.
Sources
-
Trustpilot. Halocard Reviews
-
Scamadviser. Halocard.co Trust Review
-
Ezzocard. Official Website (ezzocard.finance)
-
Ezzocard. Virtual Card FAQ
-
Trustpilot. Ezzocard Reviews
-
Monetiro. Ezzocard No-KYC Card Review
-
SmartPostly. EzzoCard Guide: Anonymous Virtual Cards & Real Costs
-
Genius Firms. EzzoCard Review: A Deep Dive Into Virtual Prepaid Cards
-
Vizovcc. Ezzocard Alternatives: Reloadable 3DS Virtual Cards
-
StatesCard. Homepage and Pricing
-
Trustpilot. StatesCard Reviews
-
US Unlocked. Homepage
-
Trustpilot. US Unlocked Reviews
-
Privacy.com. Virtual Cards (Homepage)
-
Trustpilot. Privacy.com Reviews
-
RedotPay. Homepage
-
Trustpilot. RedotPay Reviews
-
Coin Bureau. RedotPay Review 2026
-
Pay with Moon. Homepage and Ezzocard Comparison
-
Trustpilot. Pay with Moon Reviews
-
OpenCryptoCards. Moon Prepaid Card Review
-
SiraPay. Homepage and Pricing
-
MySudo. Virtual Cards
-
Trustpilot. MySudo Reviews
-
Payz. Homepage (formerly ecoPayz)
-
Merchant Machine. ecoPayz Payments Review
-
Wise. Virtual and Physical Card
-
Trustpilot. Wise Reviews
-
Revolut. Virtual Cards and Plans
-
Trustpilot. Revolut Reviews
-
Payoneer. Commercial Card and Pricing
-
Trustpilot. Payoneer Reviews
-
Airwallex. Corporate Cards and Pricing
-
Trustpilot. Airwallex Reviews
-
N26. Mastercard and Plans
-
Trustpilot. N26 Reviews
-
DoNotPay. Free Trial Virtual Credit Card
-
US Federal Trade Commission. Consumer Sentinel Network Fraud Data
Sourced on September 1, 2026
*Please see Halocard's Terms of Service or Pricing for the most up to date pricing and fee information. This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Halocard LLC or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional. We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.
Halocard Virtual Cards

Instant approval
Create your first card in under 5 minutes.

Private purchases
Purchases never appear on your bank account.

Powered by Visa
Accepted at 175M+ merchants globally.
3 steps to create your virtual credit card
1. Sign up
Create your account from a web browser. No need to download an app.
2. Verify
Verify you're a real person in 3 minutes, from the US or any of 120+ countries.
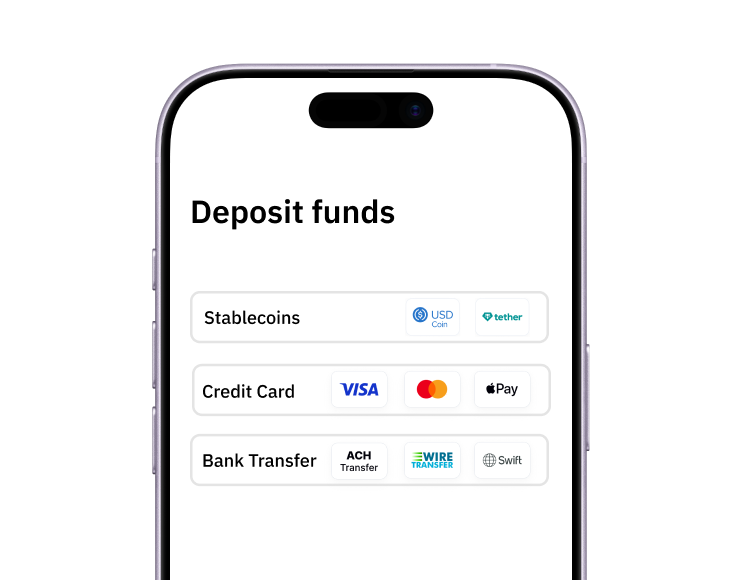
3. Fund
Add funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto.
Pay with Halocard
Pay online and in-person wherever Visa is accepted. You can also order a physical Halocard if you prefer.