Quick Answer: Revolut is once again blocking GrapheneOS users, and the GrapheneOS project says the block goes beyond standard checks. The Revolut Play Integrity setup flags GrapheneOS as an uncertified device even though the platform argues its security exceeds Google's own standards. Active sessions mostly still work, but new logins and re-authentications are blocked. A temporary workaround exists (signing into a throwaway Google account through the sandboxed Play Store), but it's not permanent.
Digital banking was supposed to make financial life easier. For a growing number of privacy-conscious users, it's doing the opposite.
Revolut, the UK-based fintech, is once again locking out people who run GrapheneOS. The Revolut GrapheneOS dispute has reignited a bigger question. What happens when your bank decides your phone isn't "trustworthy" enough to hold your own money?
Key Takeaways
- Revolut is using detection methods that specifically target GrapheneOS, according to the project, going beyond its standard Play Integrity checks.
- The Revolut Play Integrity block relies on Google's certification criteria, not actual security performance.
- This isn't isolated to GrapheneOS Revolut alone. Volkswagen, McDonald's, and several government apps have also locked out GrapheneOS devices.
- Active, already-logged-in sessions mostly keep working, but new logins and authentications get blocked.
- A temporary community workaround exists, but it tends to get patched out as Revolut updates its detection.
- If you want to avoid app-based device lockouts altogether, Halocard's browser-based virtual cards don't require installing any app, so there's no device certification check to fail.
What Happened: The GrapheneOS Revolut Ban Explained
In early August 2026, the GrapheneOS project publicly accused Revolut of deploying detection methods aimed specifically at identifying and blocking its operating system. According to Cybernews' reporting, this goes beyond the standard checks most banking apps use.
GrapheneOS argues it exceeds the security and privacy standards Revolut claims to enforce. The project has framed the ban as compliance theater rather than a response to genuine risk.
This isn't a new fight. Revolut first attempted to block GrapheneOS in January 2025, before the community found a workaround. The project says Revolut has now introduced additional, GrapheneOS-specific detection logic that broke that fix.
The Current Workaround
For now, a temporary fix exists for most affected users:
- Sign into a throwaway Google account.
- Install Revolut through the sandboxed Google Play Store rather than a direct APK.
- Complete login or re-authentication while integrity checks pass.
Revolut has not issued a public statement on the matter. GrapheneOS says active sessions mostly continue working, so the impact is concentrated on new logins and re-authentication events.
GrapheneOS Banking Apps: A Pattern, Not A One-Off
Revolut isn't the only banking or consumer app doing this. Reporting on the dispute points to several other apps enforcing similar restrictions:
- Volkswagen's companion app, which affects remote vehicle functions.
- McDonald's apps in several countries outside the US.
- Government services, authentication platforms, and digital identity apps.
The common thread across all of these GrapheneOS banking apps disputes is a single piece of technology: Google's Play Integrity API.
How Revolut Play Integrity Checks Work, And Why They Exclude Privacy-Hardened Phones
Google describes the Play Integrity API as a tool that helps developers confirm an app is running on a genuine, certified Android device. It checks that the app was installed through Google Play and hasn't been tampered with.
Developers can request different tiers of verdicts. Google explicitly recommends combining Play Integrity with other signals rather than relying on it as a sole anti-fraud mechanism.
The Certification Gap
The catch is what counts as "certified." GrapheneOS can pass basic integrity checks. It deliberately fails stronger device-certification checks because it isn't a Google-certified factory build.
That's despite the fact that GrapheneOS is specifically designed to strip out Google surveillance components and harden the OS against attacks. GrapheneOS has published its own attestation compatibility guide, which it says it shared with Revolut for years before this latest ban.
The Bigger Attestation Push
This tension isn't limited to Revolut Play Integrity checks. In July 2026, the Electronic Frontier Foundation published a critique of Google's expanded attestation push through its reCAPTCHA Mobile Verification feature.
The EFF warned that Google's remote attestation model risks locking people into a closed ecosystem. It could restrict access for anyone running de-Googled platforms like GrapheneOS or CalyxOS, according to the EFF's Deeplinks post.
More than 40 privacy-focused organizations, including Proton, Tor, and AdGuard, have separately pushed back on related Android verification policies.
Why This Is A Financial Access Problem, Not Just A Phone Problem
For most people, checking a bank balance is inseparable from having a smartphone with the "right" apps installed. That dependence is exactly why app-level bans matter so much.
Data from a Morning Consult survey commissioned by NCTA shows how deep this dependence runs:
- Nearly 9 in 10 Americans connect their smartphones to home Wi-Fi.
- Wi-Fi now carries close to 90% of all data traffic flowing over consumer smartphones in the US.
- 65% of Americans worry that limited network capacity could affect reliability going forward.
Mobile connectivity isn't a convenience layer anymore. It's the primary way people reach their money, their identity documents, and their daily services.
When a bank ties account access to a single, narrow definition of a "certified" device, it isn't just making a security decision. It's deciding who gets frictionless access to their own funds and who has to jump through workarounds instead.
What The Revolut GrapheneOS Dispute Means For Privacy-Conscious People
A few takeaways stand out from this dispute:
- Device attestation is becoming a gatekeeper for everyday services, not just high-security banking transactions. Government portals, car apps, and fast-food loyalty programs are increasingly using the same checks.
- Passing a security standard and being "Google-certified" are not the same thing. GrapheneOS argues its security model can exceed stock Android's, but that doesn't guarantee compatibility with attestation-based bans.
- Workarounds are getting harder to maintain. Each community fix tends to get detected and patched out, according to the project's own account.
- The financial industry is leaning further into single-vendor mobile dependency, even as more people actively try to reduce it for privacy reasons.
Protecting Yourself When A Banking App Turns You Away
If you're navigating this kind of lockout, or simply trying to reduce how much of your financial life depends on one phone or app, a few steps help:
- Favor providers with browser-based access. Anything that doesn't require a native app sidesteps Play Integrity checks entirely.
- Look for providers with minimal device or identity binding. Fewer dependencies mean fewer points of failure if your OS changes.
- Keep a non-attestation-dependent backup option for time-sensitive needs like bills or urgent purchases.
- Separate spending from your primary bank account so a single app-level lockout doesn't cut off all your purchasing power at once.
Where Halocard Fits In
This is exactly the gap Halocard is built to close. Halocard issues US virtual Visa cards entirely through the browser. There's no native app to install, no Play Integrity check, and no device certification requirement standing between you and your money.
You sign up from any browser, verify your identity in a few minutes, fund your account, and your card is ready to use. That includes online purchases, in-person payments through Apple Pay or Google Pay, and subscriptions at 175 million-plus merchants worldwide.
Why This Matters For GrapheneOS And Privacy-Focused Users
For anyone drawn to GrapheneOS or a similar hardened setup, Halocard's browser-first approach lines up with the same underlying goal. You keep control over your own device and your own data, without an app store or OS vendor deciding what you're allowed to access.
Halocard also doesn't run credit checks and doesn't require US residency. That matters for people who've been pushed out of mainstream banking apps for reasons that have nothing to do with their actual creditworthiness or security posture.
A Few Other Details Worth Knowing
- Cards can be locked or canceled instantly if something feels wrong, with no need to call a support line.
- Spending limits are fully self-directed. What you deposit is what you can spend, with no credit limit.
- Billing addresses can be customized, which is useful for anyone managing purchases across multiple countries.
- Support is handled by real people over chat, phone, or email rather than an automated system.
If you're weighing Halocard against other card options, this comparison of the best virtual credit card options for small businesses breaks down fees, availability, and features across several providers. If privacy is your main driver rather than business spend, this guide to how masked card services work and how to choose one is a useful next read. Full plan details are on the Halocard pricing page.
Frequently Asked Questions
Why Did Revolut Stop In Canada?
Revolut launched a limited beta in Canada in 2019 but never obtained a Canadian banking license. After 18 months of operating without the full product suite available in other markets, the company exited in March 2021, citing Canada's restrictive regulatory environment and the dominance of the country's five largest incumbent banks.
Why Does Revolut Have A Bad Reputation?
Much of Revolut's negative reputation stems from sudden account freezes triggered by automated fraud and anti-money laundering systems, paired with slow or templated customer support. Because Revolut operates as an e-money institution rather than a traditional bank in most markets, some users also report confusion around what protections actually apply to their funds.
Why Is Revolut Blocked?
Revolut isn't blocked as a service in most countries, but it does block certain users on its end, including people running GrapheneOS. This particular block is driven by Revolut's Play Integrity checks, which flag GrapheneOS as an uncertified device even though the platform itself remains fully functional and secure.
Is It Safe To Keep 100K In Revolut?
Revolut is generally an e-money institution rather than a licensed bank in the UK and EU, meaning funds are typically safeguarded rather than covered by deposit insurance schemes like the FSCS. In the US, Revolut cards are backed by a partner bank with pass-through FDIC eligibility, but coverage details and limits vary by country and account type, so it's worth confirming the specifics directly with Revolut before keeping large balances there.
Sources
-
Cybernews. GrapheneOS Says Revolut Is Blocking Users Again, And This Time It's Personal
-
Android Developers. Overview Of The Play Integrity API
-
GrapheneOS. Attestation Compatibility Guide
-
EFF. Google's New Remote Attestation Scheme Is As Bad As Its Old One
-
NCTA. Survey: Americans Rely On Wi-Fi And Want To Support Its Future Growth
Sourced on August 11, 2026
*Please see Halocard's Terms of Service or Pricing for the most up to date pricing and fee information. This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Halocard LLC or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional. We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.
Halocard Virtual Cards

Instant approval
Create your first card in under 5 minutes.

Private purchases
Purchases never appear on your bank account.

Powered by Visa
Accepted at 175M+ merchants globally.
3 steps to create your virtual credit card
1. Sign up
Create your account from a web browser. No need to download an app.
2. Verify
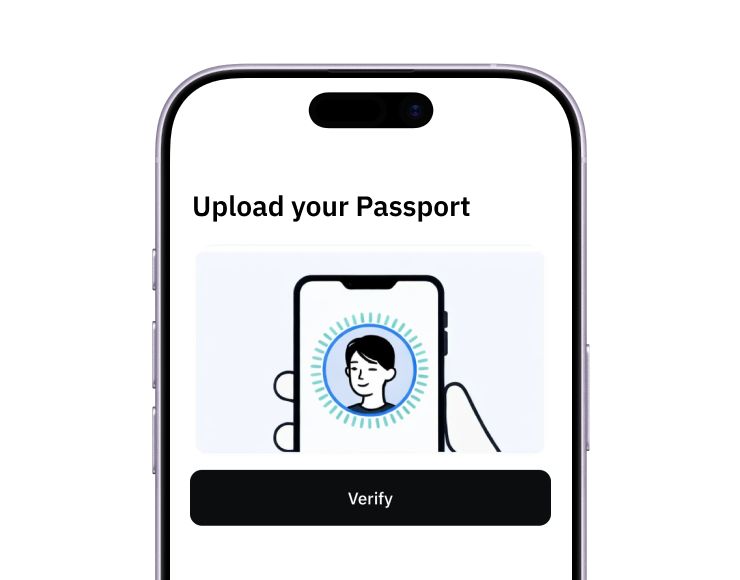
Verify you're a real person in 3 minutes, from the US or any of 120+ countries.
3. Fund
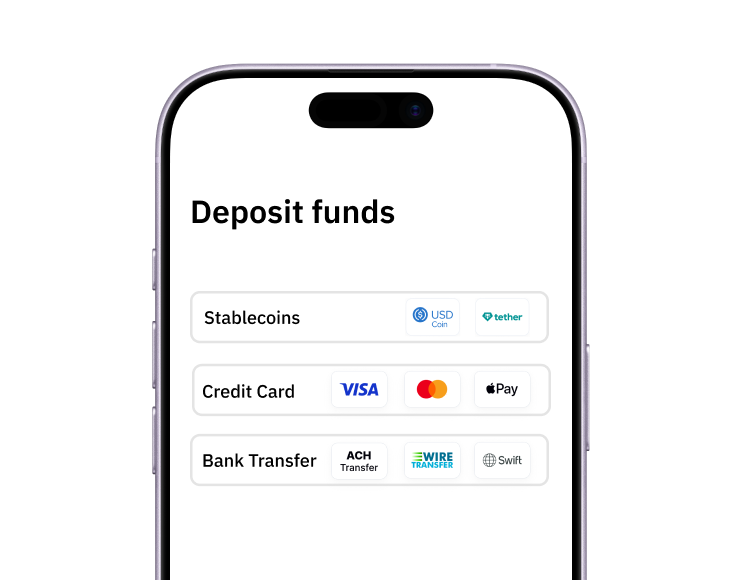
Add funds by debit/credit card, Apple Pay, Google Pay, bank transfer, stablecoins, or crypto.
Pay with Halocard
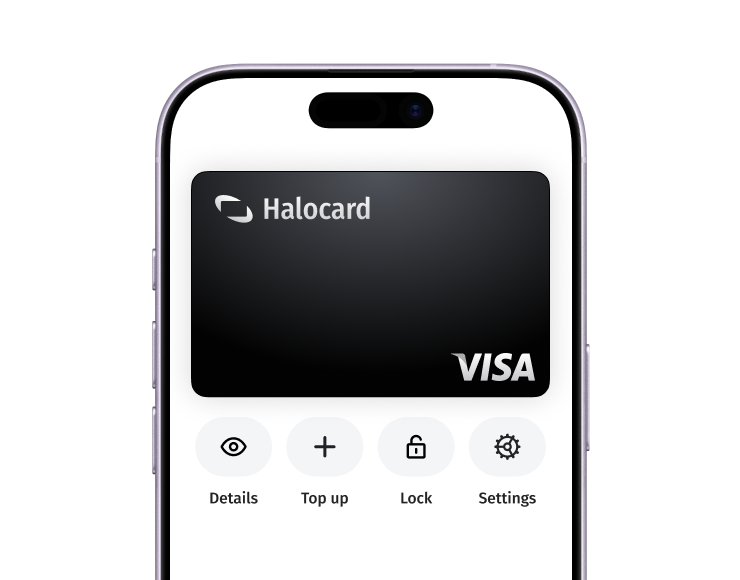
Pay online and in-person wherever Visa is accepted. You can also order a physical Halocard if you prefer.